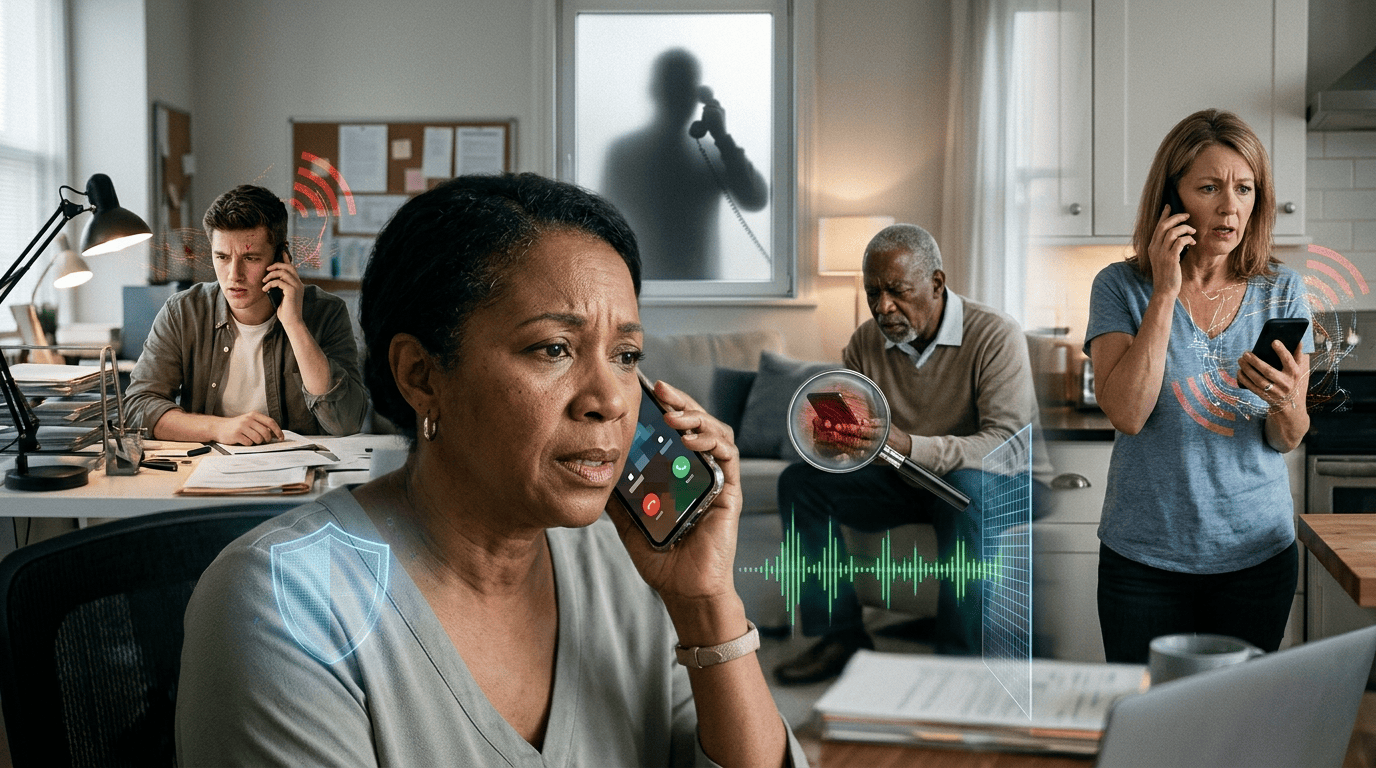
You answer an unexpected call and hear a frightening story: someone supposedly registered a phone number in your name and used it to commit crimes abroad. The person on the line claims to work for the Federal Trade Commission, quotes a badge number, and warns that your phone could be disconnected. A few minutes later, a supposed police officer takes over. Suddenly, you’re being pushed to share identification—or send money to avoid arrest.
This is not how a real FTC investigation works. It’s a government-impersonation scam described in an October 2026 FTC consumer alert. The financial danger is bigger than losing your phone service: criminals want your money, personal information, and control over the way you verify their story.
Quick Answer
If someone claiming to be from the FTC threatens to disconnect your phone, demands secrecy, asks for identification to resolve a supposed criminal case, or demands a security deposit, hang up. Do not pay or use a callback number the caller supplies—even one that appears in a search result they told you to find. Verify independently through an official .gov website. If you shared information or sent money, contact the affected financial institution immediately and begin appropriate identity-protection steps.
Knowledge Snapshot
- The FTC says it does not demand money, threaten to disconnect your phone, or tell you to keep an investigation secret.
- A fake badge number, police transfer, and even a staged callback can be parts of the same scam.
- Your response depends on what you lost: a card number, password, ID document, Social Security number, or money each requires different steps.
- A credit freeze helps prevent some new-account fraud; it does not secure your existing accounts or phone number.
- Your safest verification method is to end the call and start a completely new contact through an independently found official channel.
How the fake FTC investigation becomes a money trap
According to the FTC’s warning, the first caller alleges that a phone registered under your name is connected to scams in another country. The caller may offer a fake badge ID, transfer you to an impersonator posing as a police officer, and instruct you to search for a police-department telephone number. That last step is especially deceptive: you feel as though you’re independently checking the story when the instructions actually direct you back to people involved in the fraud.
Next come requests for identification, personal data and secrecy. The stakes escalate to a fictitious arrest and the claim that you must travel abroad—unless you pay a so-called security deposit. Every step is designed to transform fear into compliance. The scammer’s real question isn’t whether you committed a crime. It’s how much money or identifying information you can be persuaded to surrender.
The overlooked trick: a callback can be fake verification
Most people know not to trust caller ID. Fewer recognize that a caller can choreograph an entire ‘verification’ process. Consider a hypothetical example: Mia gets the scary FTC call. The impostor tells her to search for ‘police case department’ and call the first number in a specific result. A second person answers, repeats her name and case number, and tells her the report is legitimate. Mia has made a call herself—but she hasn’t verified anything independently, because the scammer selected the search terms, number and supposed department.
A better rule is to verify the institution, not the story the caller scripted. Hang up. Open a government agency’s official website without using links or instructions provided during the call. If someone claims to be your bank, use the number on your card or bank statement. A real organization should be able to confirm whether there is a genuine issue through its established channels.
What should you say before hanging up?
Keep it short: ‘I don’t share information or send money on unexpected calls. I’ll contact the agency independently if there’s a real issue.’ Then end the call. You do not need to argue about the badge ID, explain your finances, or prove that you’re innocent. And do not stay on the line while you search for a number; the person threatening you should not control your next step.
If you shared information, match the response to the exposure
Use this recovery checklist instead of taking every possible step indiscriminately:
- Name, phone number or address only: expect more personalized scam calls; do not treat callers knowing these details as proof of legitimacy. Watch for follow-up texts and emails.
- Bank password, login credentials or one-time code: immediately contact the bank or service using its official number, secure the account, change exposed or reused passwords, review recent activity, and ask whether access should be revoked or accounts restricted.
- Debit or credit card number: contact the issuer’s fraud department promptly, ask about replacement and disputed charges, and enable transaction alerts.
- Social Security number or identifying documents: use IdentityTheft.gov for a tailored recovery plan; consider freezes at Equifax, Experian and TransUnion, and contact the issuing agency as appropriate.
- Mobile-carrier account information: ask the carrier about an account PIN, SIM-swap safeguards or a port-out lock. A credit freeze does not prevent a criminal from transferring your mobile number.
Here’s a second hypothetical situation. David sends a photo of his driver’s license but pays nothing. He should not assume ‘no money lost’ means no risk. He can record what was exposed, contact the issuing agency about recommended precautions, review his credit activity and consider freezes. If David also gave a banking password, securing that account becomes the immediate first priority. The action plan follows the exposure, not a one-size-fits-all warning.
If you already paid a fake security deposit
Act quickly, even if you’re embarrassed or unsure whether a refund is possible. Call your bank, card issuer, payment app or transfer provider using an independently verified number. Tell them precisely when, how much and how you paid, and ask whether a transfer can be stopped, recalled or disputed. Keep transaction IDs, recipient details, messages and screenshots. The available protections differ for cards, bank transfers, wires, cash and cryptocurrency; recovery is never guaranteed.
For example, if you were pressured to send $2,400 by bank transfer yesterday, do not spend the morning arguing with the caller. Call the bank’s fraud team first, describe the impersonation, ask about available reversal or recall options, and record the case number. Then secure any compromised credentials and report the scam. Time can matter, but the bank—not a supposed ‘recovery agent’ who demands another fee—is the place to begin.
A four-question test before believing an official-sounding caller
ATMC’s broader scam coverage uses an Identity–Proof–Channel–Pressure framework. Apply it here:
- IDENTITY: Can you verify the alleged agency using an official source you found yourself?
- PROOF: Is there any case or notice you can confirm outside the caller’s paperwork or badge number?
- CHANNEL: Is the caller directing you to a particular number, website or person they control?
- PRESSURE: Are you being threatened with immediate arrest, disconnection, secrecy or payment?
If the story fails any test, stop the conversation and independently check before taking financial action.
For related guidance, ATMC explains why an initial exposure can trigger more attempts in ‘Scammed Once? Why the Calls Keep Coming and How to Break the Loop’ (https://askthemoneycoach.com/stop-repeat-scam-calls/) and how to recognize government-impostor recovery demands in ‘Avoid Suckers List Scams Targeting Previous Fraud Victims’ (https://askthemoneycoach.com/suckers-list-scam/).
Where to report the incident
Report the approach at https://ReportFraud.ftc.gov. If your identity was misused, use https://IdentityTheft.gov to create a recovery plan. For cyber-enabled financial crime, consider reporting to the FBI’s Internet Crime Complaint Center at https://www.ic3.gov/. Save the fraudster’s messages, numbers and transaction records, but don’t call back or revisit suspicious links simply to collect evidence. Reports help document the problem; they do not promise reimbursement.
Protect your money, not the caller’s invented deadline
The lesson is not that every official call is fake. It’s that the person who starts an unexpected call should not be allowed to define your deadline, choose your verification channel and decide where your money goes. End the call, independently verify, and protect whatever information or funds were exposed. That small change in who controls the next step can stop a frightening story from becoming a financial loss.
FAQs: Fake FTC Phone Call Scam
Can the FTC legally disconnect my cellphone because of an overseas scam?
The FTC says its employees do not threaten to disconnect your phone as part of the impostor-call scenario described in its October 2026 alert. Treat that threat as a scam warning and verify any real service issue directly with your carrier.
What if the caller knows my full name, address or phone number?
Those details can come from public records, data breaches or earlier scams. Familiar personal information is not proof of official identity. End the call and verify through a trusted channel.
Is an FTC badge number evidence that a call is genuine?
No. Scammers can invent badge numbers and send fake ID images. The FTC specifically warns that an impostor may read off a false badge ID to make the threat sound credible.
What if I called the ‘police department’ number myself?
A callback is not independent verification when the original caller tells you exactly what to search for or whom to call. Find the agency’s official contact information on your own and start a separate inquiry.
Should I freeze my credit if I only answered the call?
Simply answering does not necessarily expose identity information. A freeze becomes especially relevant if sensitive identifying information such as a Social Security number was disclosed. Assess what the caller obtained before choosing safeguards.
Does freezing my credit stop a SIM-swap or phone-number transfer?
No. A credit freeze affects access to consumer credit reports for many new-credit applications. Ask your mobile carrier about a port-out PIN, account lock or other protection against unauthorized number transfers.
Can I get back money I sent to a fake government official?
Possibly, depending on the payment method, timing and circumstances, but there is no guarantee. Promptly contact the bank, card issuer or payment service and ask about applicable disputes, recalls or other recovery options.
What should I do if I gave the caller a one-time verification code?
Contact the account provider immediately through its official app or phone number. Explain that a code was disclosed, review account activity, change compromised credentials and ask about locking or recovering the account.
Will reporting to the FTC automatically stop the scam calls?
No. Reporting documents the attempt and can support enforcement activity, but it does not guarantee that calls will stop. Continue using independent verification and secure any exposed accounts.
Should I change my phone number after an impostor call?
Not automatically. First ask the carrier about account security and port-out protection, and be cautious about future contacts. Consider a number change only if ongoing harassment or account risks make it worthwhile after discussing options with the carrier.

Avoid This Scam™ is the consumer protection and scam awareness desk of AskTheMoneyCoach.com. We help readers recognize, avoid, and respond to financial scams, fraud, identity theft, deceptive business practices, and online threats.
Our coverage includes scam alerts, fraud prevention strategies, consumer advocacy, practical safety guides, and expert analysis designed to help individuals and families protect their money, personal information, and financial well-being. We also explain what to do if you’ve already been targeted, because knowing how to respond can be just as important as avoiding a scam in the first place.