A new survey found that 45% of Gen Z adults with debt said their debt increased during the past 12 months, the highest share of any generation surveyed. That compared with 39% of millennials, 34% of Generation X, and 30% of baby boomers.
The most important insight is not simply that Gen Z owes money. It is that debt is consuming different milestones at different ages.
For a younger adult, a monthly debt payment may delay a first home, a career move, or starting a family. For someone in their 50s, the same cash flow commitment may reduce retirement savings. For a retiree, it may limit spending flexibility.
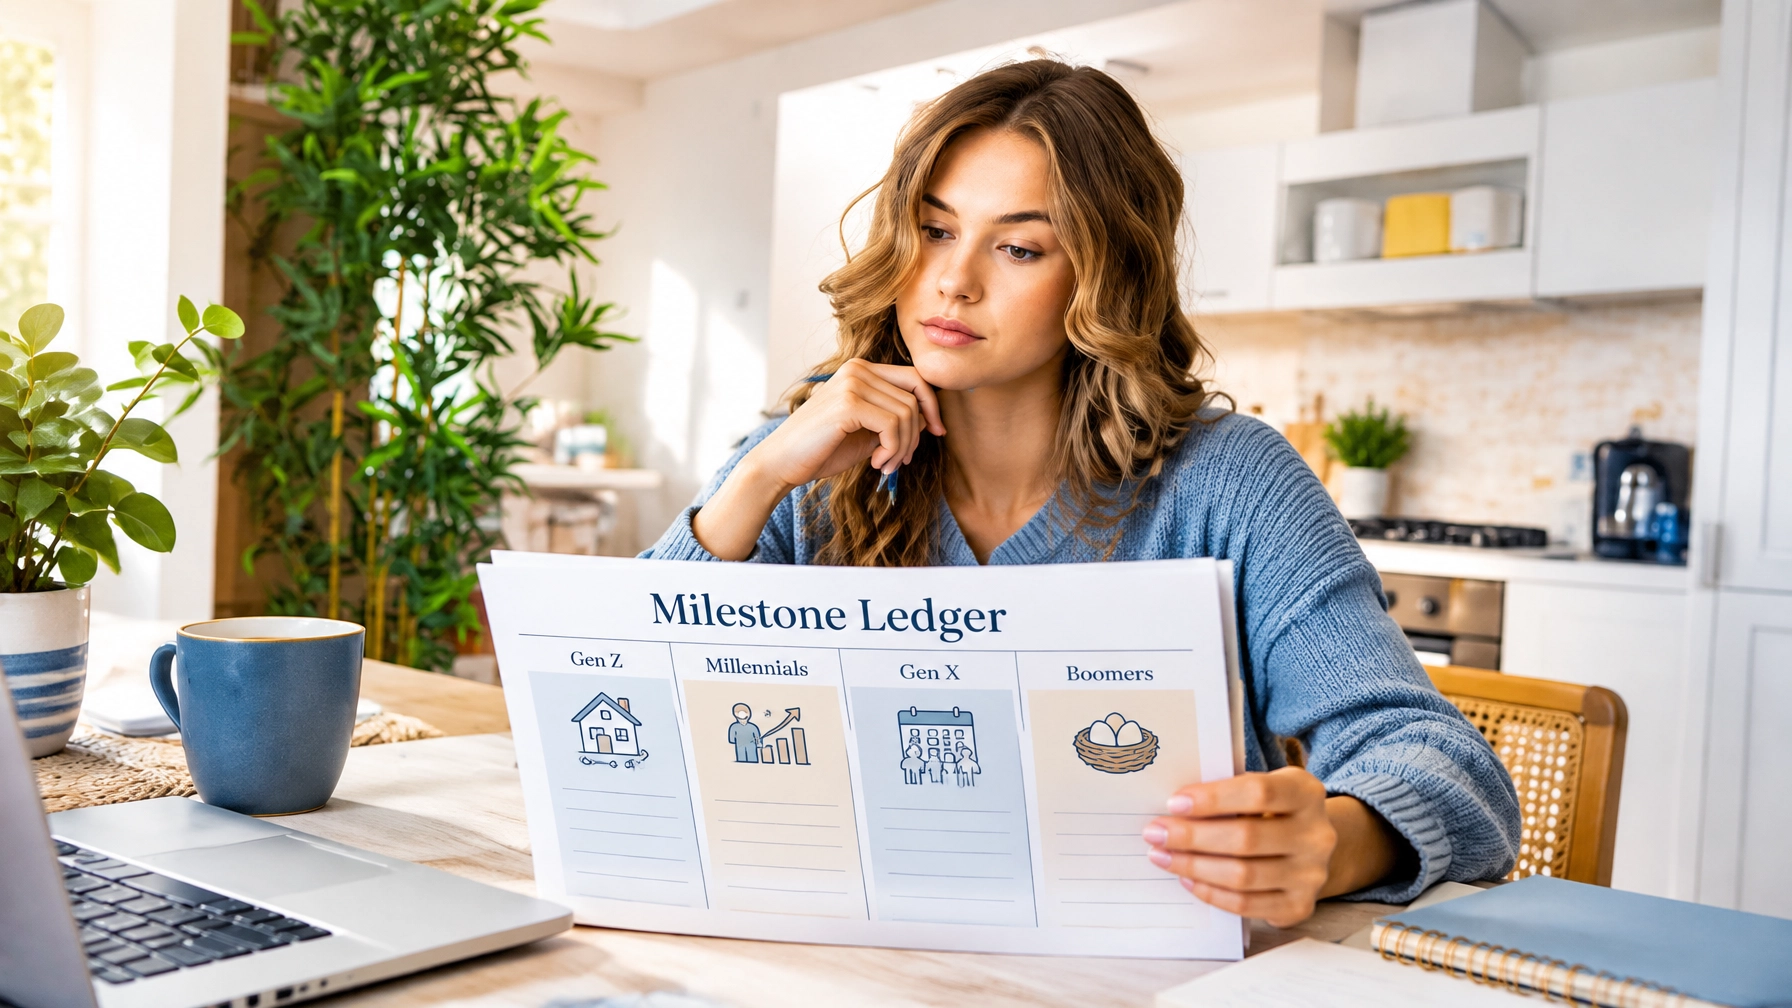
This article uses a milestone ledger to examine what debt is costing each generation beyond interest.
Important source note: The primary study was company-sponsored, lead-generation research. It was produced by aytm on behalf of Accredited Debt Relief, a debt consolidation company, and Money.com, a commercial publisher. It should not be treated as neutral academic or government research. The findings are useful for understanding self-reported debt trends and financial stress, but they do not prove that one generation is financially irresponsible or establish cause and effect.
Quick Answer
Gen Z’s debt is growing faster because many young adults are entering the credit system during a period of high housing costs, inflation, expensive education, and limited early-career financial cushions.
The survey also found that 51% of Gen Z respondents cited a lack of financial education as a contributor to their debt, while 55% cited recent changes to laws, taxes, and government programs. However, the results do not support the idea that Gen Z is simply worse with money than older generations.
The more useful question is this:
What milestone is your debt currently consuming?
That question shifts the conversation away from shame and toward cash flow, choices, and a realistic plan.
Why Trust This Article
This article relies primarily on the September 22, 2026 study from Accredited Debt Relief and Money.com, along with its associated press release.
The survey was:
- Conducted by aytm in July 2026
- Sponsored by Accredited Debt Relief and Money.com
- Based on a nationally representative sample of 2,000 U.S. adults
- Limited to adults who reported having some type of debt during the past year
- Organized by birth year, with Gen Z defined as 1997 to 2012, millennials as 1981 to 1996, Generation X as 1965 to 1980, and baby boomers as 1946 to 1964
Because the sponsor is a commercial debt consolidation company, the research may have a marketing purpose. The survey measures what respondents reported about their debt, stress, and behavior. It does not independently verify balances, income, or repayment records.
For separate context, the Federal Reserve Bank of New York’s Q2 2026 Household Debt and Credit Report reported that U.S. credit card balances reached $1.263 trillion, while total household debt decreased slightly to $18.771 trillion. That government data point is independent of the Accredited Debt Relief and Money.com study. It does not measure the same issues, but it confirms that household borrowing remains a significant national cash flow concern.
Editorial Perspective: Read Debt as a Milestone Ledger
Most debt discussions focus on balances, interest rates, and credit scores. Those numbers matter, but they can miss the personal cost.
A debt balance also creates a ledger of postponed decisions.
Consider two people who each have a $20,000 balance and a $400 monthly payment. The dollar amount is the same, but the economic cost may be very different.
- A 25-year-old may be giving up $400 that could fund a home down payment, professional training, a move to a better job market, or a starter emergency fund.
- A 50-year-old may be giving up $400 that would otherwise go into retirement savings or help eliminate a mortgage before leaving the workforce.
- A retiree may be using $400 that would have paid for health care, home repairs, travel, or basic household flexibility.
The debt does not just charge interest. It competes with the next milestone.
Bobbi Rebell, the company’s Chief Financial Education Advisor and a CFP, summarized the issue this way: “What stands out here is that debt hits differently in different life stages.”
That is the central finding worth carrying forward. Generational debt comparisons should not be used to rank who is good or bad with money. They should help explain what financial pressure looks like at different points in life.
The Debt Milestone Ledger by Generation
| Generation | Debt rose in past year | Often or always stressed | Optimistic about payoff | Milestone delayed or threatened | Retirement saving cut |
|---|---|---|---|---|---|
| Gen Z | 45% | 60% | 28% | Homeownership, career moves, and family planning | 24% |
| Millennials | 39% | 56% | 27% | Homeownership and family-related goals | 34% |
| Gen X | 34% | 51% | 37% | Retirement readiness | 41% |
| Baby boomers | 30% | 36% | 48% | Retirement spending flexibility | 26% |
Source: Accredited Debt Relief and Money.com study, conducted by aytm in July 2026.
The table shows why one headline percentage cannot tell the whole story.
Gen Z: Debt spends future options
Gen Z had the highest reported debt growth and stress, but the lowest optimism about paying it off among the four groups.
Thirty-eight percent said debt delayed saving for or buying a home. The study also reported that debt was delaying career moves and plans to start a family for younger adults.
Gen Z respondents were more likely than older generations to take on a side gig, borrow from family, draw down savings, or delay payments to manage debt. Twenty-seven percent said they took a side gig during the past year.
This can create a difficult cycle. Extra work may help produce cash today, but it also takes time away from education, health, relationships, and career development. If a side gig becomes the only way to make minimum payments, the problem is not simply a spending problem. It is a cash flow problem.
Millennials: Debt competes with family finances
Millennials reported the second-highest rate of debt growth and stress. Thirty-one percent said debt delayed saving for or buying a home.
This generation is also dealing with multiple financial responsibilities at once. Sixty-eight percent of millennials cited low wages or job loss as a contributor to debt. More than half cited the cost of raising children or caring for elderly family members.
That creates a crowded milestone ledger. Debt may compete with a home down payment, child care, education savings, elder care, and retirement contributions at the same time.
Generation X: Debt spends retirement time
Gen X reported the highest rate of cutting retirement savings because of debt, at 41%.
This is a different kind of urgency. A younger borrower may have decades to recover from a delayed investment contribution. A Gen X borrower has fewer working years for compound growth to do its work.
That does not mean every Gen X borrower should stop retirement contributions and direct every dollar to debt. It does mean the tradeoff deserves an honest calculation. A high-interest credit card balance can be financially damaging, but abandoning an employer retirement match may also create a costly opportunity loss.
Baby boomers: Debt reduces flexibility
Baby boomers were the only generation more likely to report decreasing debt than increasing debt. They also reported the lowest stress level and the highest optimism about repayment.
Still, lower debt growth does not mean no pressure. Debt during retirement can reduce the ability to respond to medical bills, home repairs, inflation, or changes in investment income.
For a retiree, the milestone ledger may not show a delayed home purchase. It may show fewer choices. A debt payment can make it harder to adjust spending when income is fixed.
What Is Driving the Debt?
The survey found that respondents pointed to broad economic conditions more often than their own borrowing decisions:
- 78% cited inflation as a major contributor
- 68% cited housing costs
- 66% cited their own spending or borrowing decisions
The findings do not eliminate personal responsibility. They provide context. A household can make poor borrowing decisions and still be affected by rising costs. Both things can be true.
Gen Z’s responses also point to a knowledge gap. Fifty-one percent cited a lack of financial education. That does not mean financial education alone would solve the problem. Knowing how credit works cannot make rent, tuition, or groceries less expensive. But financial knowledge can help people recognize when a payment is consuming a milestone before the debt becomes unmanageable.
The survey found that money habits are also influenced by family history. Sixty-three percent of Gen Z respondents said their parents shaped their debt habits, and 67% wanted different habits from their parents. Gen Z was also more likely than older generations to discuss debt with family or friends, although only half of all respondents said they had always been fully honest about how much they owed.
What Your Debt Is Actually Spending
Try this milestone ledger exercise before choosing a payoff strategy.
Step 1: List every required debt payment
Include credit cards, student loans, auto loans, personal loans, buy now, pay later balances, and any other recurring obligations.
Step 2: Calculate the annual cash flow
If your required debt payments total $300 per month, that is $3,600 per year. Over five years, the payments equal $18,000 before interest and new borrowing.
Step 3: Name the milestone being crowded out
Complete this sentence:
“My debt is currently spending money that I intended to use for __________.”
Your answer might be:
- A home down payment
- A career certification
- Relocating for a better job
- Starting or expanding a family
- Retirement contributions
- A reliable vehicle
- Medical care
- A basic emergency fund
- The ability to reduce work hours
Step 4: Identify the balance that creates the most risk
The largest balance is not always the most urgent. A high-interest credit card may deserve priority over a lower-rate student loan. A debt with a variable rate may create more uncertainty than a fixed-rate obligation. A delinquent account may require immediate attention because of fees, credit damage, or collection activity.
Step 5: Protect the milestone while paying down debt
A debt plan that drains your entire emergency fund may look aggressive but leave you vulnerable to the next car repair, medical bill, or job interruption.
As Rebell said, “Paying down debt aggressively makes sense, but it shouldn’t come at the cost of having a financial safety net.”
The goal is not to preserve every financial goal at full speed. It is to decide consciously which goals can slow down, which must continue, and which debt requires immediate action.
What This Means for You
Whether you are Gen Z, a millennial, Gen X, or a baby boomer, use your own milestone ledger instead of comparing yourself with another generation.
Start with these actions:
- Build a complete debt list. Record balances, interest rates, minimum payments, and due dates.
- Separate essential and discretionary spending. Cutting restaurant meals or clothing may help. Cutting groceries, medical care, transportation repairs, or insurance can create new risks.
- Keep a starter emergency reserve. Even a modest cash buffer can reduce the need to borrow for a minor surprise.
- Pay at least the minimum on every account. Then direct extra cash toward the debt that best matches your priorities.
- Review retirement contributions carefully. If possible, preserve an employer match while directing additional money toward expensive debt.
- Use extra income strategically. A side gig can help, but it should support a defined plan rather than become a permanent substitute for affordable monthly cash flow.
- Talk honestly with someone you trust. Secrecy can delay useful decisions and allow balances to grow.
ATMC resources that may help:
- Debt payoff strategies and tactics
- Budgeting tips for families
- Financial resilience and emergency savings planning
- Planning for retirement while paying off debt
ATMC Money Coach Box: Do not measure progress only by the balance.
Ask what your debt payoff will make possible. A lower balance may restore emergency savings, open a career opportunity, protect retirement contributions, or bring homeownership back into view. The milestone is part of the return on your financial effort.
Frequently Asked Questions
Why is Gen Z accumulating debt faster?
The survey found that 45% of Gen Z respondents with debt said their debt increased during the past year. Gen Z respondents cited inflation, housing costs, limited financial education, and changes to laws, taxes, and government programs. Many are also entering adulthood with lower early-career income and smaller savings cushions, making it easier for an unexpected expense to become borrowed money.
Is Gen Z worse with money than other generations?
The survey does not prove that. It measures self-reported debt changes, stress, and behavior among adults who had debt. Gen Z also reported more willingness to discuss debt, take side gigs, and develop different habits from their parents. Faster debt growth may reflect economic conditions and life stage as much as personal behavior.
Should I cut retirement savings to pay off debt?
It depends on the interest rate, employer match, tax consequences, and your broader cash flow. High-interest debt may deserve aggressive repayment, but giving up an employer match can also be costly. A balanced approach may preserve the match, maintain a starter emergency fund, and direct additional money toward expensive debt.
Should I use my emergency fund to pay off debt?
Usually, do not drain your emergency fund completely. Paying off debt and then borrowing again for an urgent repair can leave you worse off. Keep an appropriate cash reserve, then consider using money above that reserve for repayment if the debt interest rate is high and your income is stable.
Does debt really delay buying a home?
It can. Debt payments reduce the cash available for a down payment and closing costs. They can also affect debt-to-income calculations used by mortgage lenders. In the survey, 38% of Gen Z and 31% of millennials said debt delayed saving for or buying a home.
How do I pay off debt faster?
Start by paying minimums on every account, then choose a method for directing extra money. The debt avalanche targets the highest interest rate first and may reduce total interest. The debt snowball targets the smallest balance first and may create faster psychological wins. Use a budget to find repeatable cash flow, not just one-time cuts.

Surveys That Count™ is AskTheMoneyCoach.com’s research and insights desk, featuring original surveys, third-party studies, and data-driven reports relevant to consumers, businesses, investors, entrepreneurs, and financial decision-makers.