Knowledge Snapshot
- An inheritance can be exposed to an heir’s creditors, lawsuit claims, divorce proceedings, or bankruptcy.
- Probate avoidance and creditor protection are related, but they are not the same thing.
- A non-spouse inherited IRA is generally not protected by the federal bankruptcy exemption under Clark v. Rameker.
- A surviving spouse may be able to roll an inherited IRA into the spouse’s own IRA, which changes the account’s legal treatment.
- Life insurance, payable-on-death accounts, and transfer-on-death accounts often bypass probate. That does not automatically protect the money from the beneficiary’s creditors.
- Properly drafted trusts may provide stronger protection because the beneficiary does not receive unrestricted ownership immediately.
- State law can change the result, especially for inherited IRAs, life insurance, homestead property, and joint accounts.
Quick Answer
Can an inheritance be taken by an heir’s creditors? Sometimes.
The answer depends on the asset, how it passes to the heir, the heir’s state of residence, and whether the heir faces ordinary collection efforts, a lawsuit, divorce, or bankruptcy.
The most vulnerable assets are generally ordinary cash, inherited real estate, and non-spouse inherited IRAs received outright. Assets held in a properly drafted trust may receive greater protection, but no structure is automatically creditor-proof.
Why Inheritance and Creditor Protection Are Two Different Questions
Estate planning answers one question: Who receives the property after death?
Creditor protection answers another: Can that person’s creditors reach the property after receiving it?
For example, a payable-on-death bank account may transfer directly to a named beneficiary without probate. That can keep the account away from the deceased owner’s probate estate and may reduce exposure to the deceased owner’s creditors. But once the beneficiary receives the funds, they generally become part of the beneficiary’s financial life.
If the beneficiary has unpaid judgments, significant debt, a pending lawsuit, or a divorce, the money may be at risk under state law.
The key distinction is this:
Avoiding probate can control the path an asset takes. It does not necessarily create a shield around the heir.
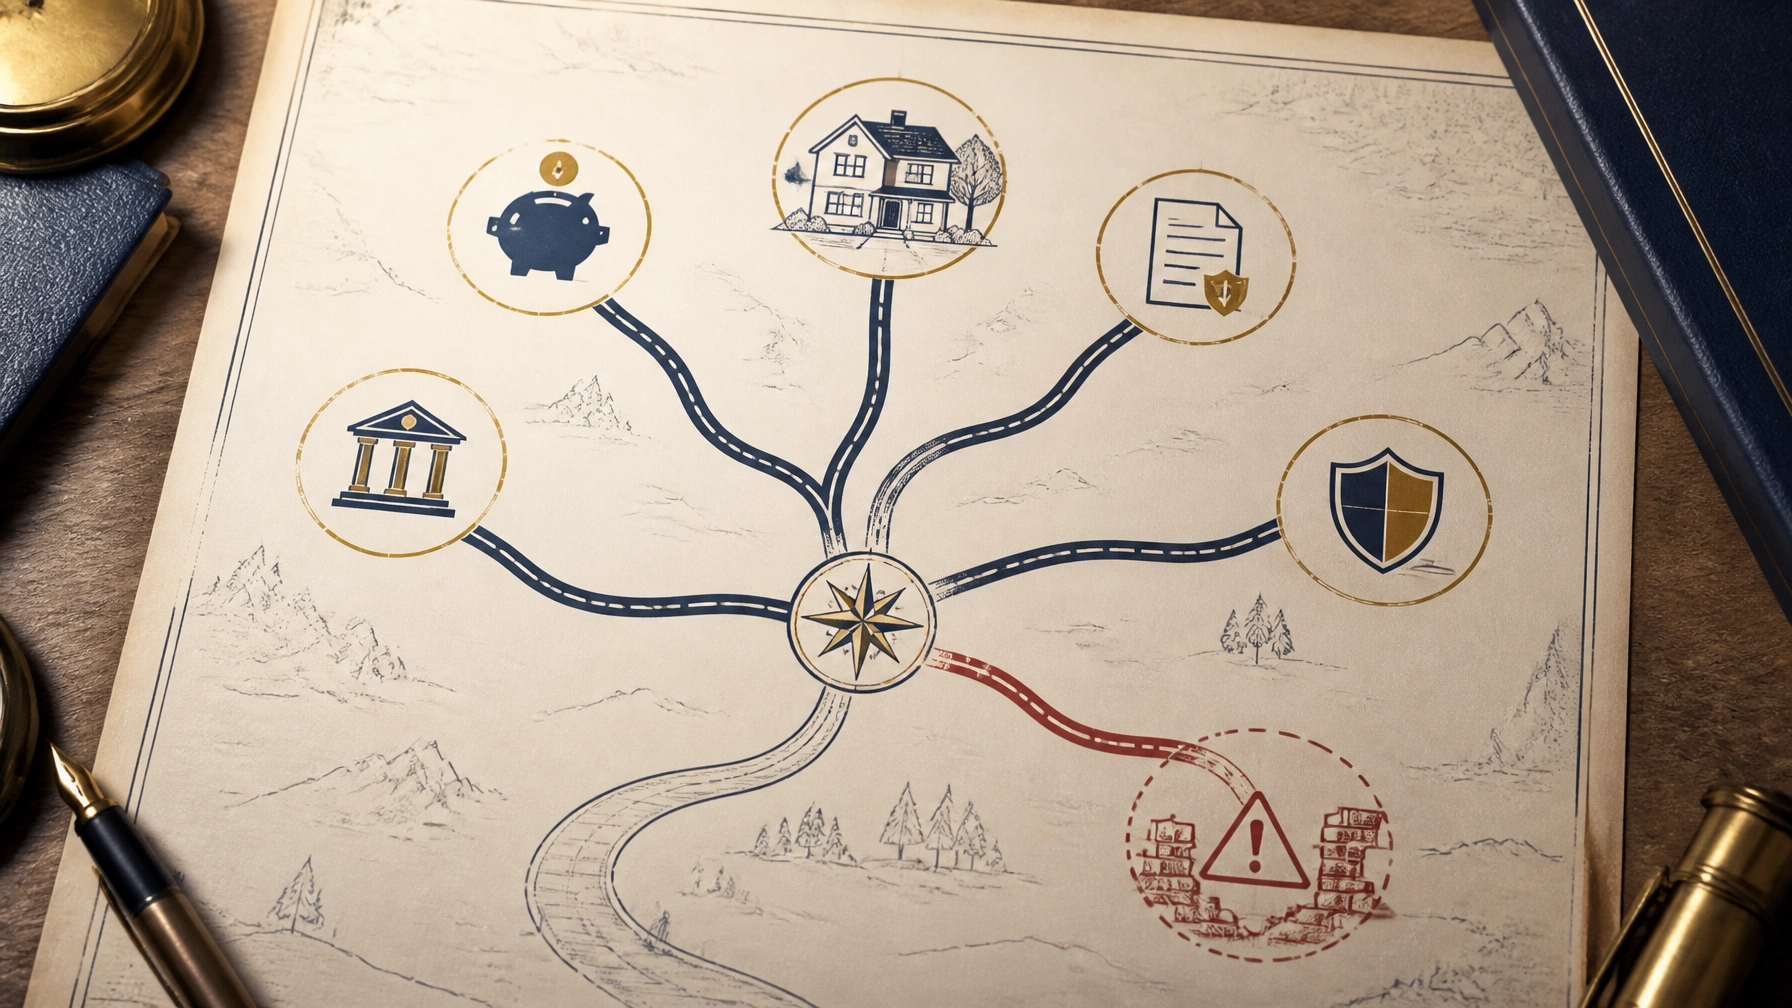
The Asset-by-Asset Map
| Asset type | Typical exposure to an heir’s creditors | Main planning issue |
|---|---|---|
| Non-spouse inherited IRA | High in federal bankruptcy | Clark v. Rameker and state exemptions |
| Spousal rollover IRA | Often stronger protection | Proper rollover and beneficiary status |
| Life insurance proceeds | Highly state-specific | Beneficiary designation and trust ownership |
| POD or TOD account | Often exposed after transfer | Probate avoidance is not creditor protection |
| Real estate | Often exposed after inheritance | Homestead rules, liens, and title |
| Trust assets | May be better protected | Trust language and trustee discretion |
| Ordinary cash | Usually exposed | Direct ownership and account structure |
Inherited IRA, Non-Spouse
A child, grandchild, sibling, or other non-spouse beneficiary generally cannot treat an inherited IRA as their own IRA. The account must remain an inherited account and is subject to distribution rules.
In federal bankruptcy, this distinction is critical. In Clark v. Rameker, the U.S. Supreme Court held that inherited IRA funds are not “retirement funds” for purposes of the federal bankruptcy exemption. The Court focused on three features:
- The beneficiary cannot make new contributions.
- Distributions are required regardless of the beneficiary’s age.
- The beneficiary can withdraw the entire balance without the early withdrawal penalty that generally applies to an owner’s IRA.
As a result, a non-spouse inherited IRA is generally reachable in bankruptcy under federal law.
State law may provide a different result. Texas, for example, has a statute that expressly includes inherited IRAs in its retirement account exemption. Pennsylvania courts, by contrast, have treated inherited IRAs as outside the state’s retirement account protection. Residency and bankruptcy exemption rules also matter.
Spousal Rollover IRA
A surviving spouse typically has more options than a non-spouse beneficiary. The spouse may be able to roll the inherited IRA into the spouse’s own IRA rather than keeping it as an inherited account.
That change can restore the account’s character as the spouse’s retirement fund. It may therefore receive stronger protection under federal bankruptcy law and state exemption law.
The result is not automatic. The spouse must follow the applicable rollover rules, and the account may still be subject to exceptions, liens, or state-law limitations. A spouse who leaves the money in an inherited IRA may not receive the same treatment as a spouse who properly rolls it into an IRA owned by the spouse.
Life Insurance Proceeds
Life insurance often passes directly to a named beneficiary and avoids probate. Many states also provide special protection for policy proceeds, particularly when the beneficiary is a spouse or dependent.
However, protection varies widely. Once proceeds are paid outright to an adult child or other beneficiary, the money may become a general asset available to the beneficiary’s creditors.
A trust may allow the policy proceeds to remain under trustee control. Trust provisions such as spendthrift restrictions and discretionary distributions may reduce exposure to a beneficiary’s creditors or divorcing spouse. An irrevocable life insurance trust can also raise separate tax and ownership issues, so it should be designed with an estate-planning attorney.
Payable-on-Death and Transfer-on-Death Accounts
POD bank accounts and TOD investment accounts generally transfer outside probate to the beneficiary listed on the account.
That is useful for speed and administration. It is not a complete creditor-protection strategy.
After the beneficiary receives the funds, the money is usually subject to the beneficiary’s own creditor claims under state law. A creditor may also challenge transfers made to evade existing debts. Naming a beneficiary directly can keep the account out of the deceased owner’s probate estate, but it does not make the beneficiary financially invisible.
Real Estate
Inherited real estate can be exposed to an heir’s creditors once the heir receives an ownership interest. A creditor may be able to place a lien on the property or pursue the heir’s equity, depending on state law and the nature of the debt.
The heir may receive some protection if the property qualifies as a homestead or another exempt category. That protection is highly state-specific and may depend on occupancy, acreage, ownership structure, and the type of creditor.
Real estate also carries obligations that do not disappear at death, including mortgages, property taxes, insurance, homeowner association assessments, and maintenance costs.
Trust Assets
A properly drafted trust may offer the strongest practical protection for an heir who may face creditor, divorce, or lawsuit risk.
The trust can hold assets for the beneficiary without giving the beneficiary unrestricted ownership. A trustee may be authorized to distribute money for health, education, maintenance, or support while refusing to make a distribution that would immediately be captured by a creditor.
But not every trust protects the beneficiary. A revocable trust controlled by the beneficiary generally offers little protection from that beneficiary’s creditors. Even an irrevocable trust can have limits, especially for child support, alimony, government claims, or debts connected to the beneficiary’s own misconduct.
Trust planning must also coordinate with retirement account tax rules. A trust that is appropriate for ordinary investments may not be appropriate as an IRA beneficiary.
The Rule That Surprises People: Clark v. Rameker
The Supreme Court’s 2014 decision does not mean every inherited IRA is unprotected everywhere. It means that an inherited IRA is not automatically protected under the federal bankruptcy exemption for retirement funds.
State exemption laws can supplement or change the result. Some states expressly protect inherited IRAs. Others protect ordinary retirement accounts but exclude inherited accounts.
This is why the heir’s state of residence matters. Before moving money, changing account ownership, or filing bankruptcy, the beneficiary should obtain advice from a bankruptcy attorney or estate-planning attorney familiar with local law.
Probate vs. Creditor Protection: What Actually Happens in Court
Probate is the court-supervised process for transferring assets that do not pass through a beneficiary designation, joint ownership arrangement, trust, or another non-probate method.
Probate may expose assets to claims against the deceased person’s estate. It does not automatically protect property from the heir’s creditors.
An asset may avoid probate and still be vulnerable after transfer. Conversely, a trust asset may avoid probate while remaining under trustee control rather than becoming the beneficiary’s unrestricted property.
Think of probate as an estate administration system, not a universal creditor shield.
Why Beneficiary Forms Can Override a Will
For many retirement accounts, life insurance policies, and financial accounts, the custodian’s or insurer’s beneficiary designation controls the transfer.
If a will leaves an IRA to one person but the IRA beneficiary form names someone else, the beneficiary form generally controls. A will typically governs only assets that remain in the probate estate.
Review beneficiary forms after marriage, divorce, births, deaths, remarriage, major account changes, and trust updates. A current will cannot repair an outdated beneficiary designation.
The Family Review Checklist Before Death
Ask these questions for every major asset:
- Who is listed as the primary beneficiary?
- Who is the contingent beneficiary?
- Does the designation match the current will and trust?
- Is a beneficiary facing bankruptcy, divorce, lawsuits, or serious debt?
- Would direct ownership create unnecessary exposure?
- Should a trust receive the asset instead?
- Does the beneficiary live in a state with different exemption rules?
- Are there mortgages, liens, taxes, or other obligations attached?
- Have the tax consequences of inherited retirement accounts been reviewed?
- Does the estate plan need an attorney, tax professional, or financial planner to coordinate the details?
For a broader review of managing inherited money, see 7 Ways to Avoid Blowing Your Inheritance. Families considering long-term wealth structures may also benefit from How the Rich Use Inheritance Management.
What to Do This Week
Create a one-page inventory of every account, policy, property, trust, and beneficiary designation. Mark each asset as passing by probate, contract, joint ownership, or trust.
Then identify any heir with significant debt, a pending lawsuit, bankruptcy concerns, or divorce exposure. Do not change ownership or transfer assets after a claim has already arisen without legal advice. Transfers intended to hinder creditors can create additional legal problems.
FAQ: Inheritance Protection From Creditors
Can creditors take an inheritance before it is distributed?
They may be able to reach an inheritance through the deceased person’s estate, depending on the debt and state law. If the asset passes directly to the beneficiary, the deceased person’s creditors may have less access, but the beneficiary’s creditors may gain access after transfer.
Can credit card companies take inherited money?
Possibly. If the heir has a judgment or collection action, ordinary cash and unrestricted inherited funds may be reachable under state law.
Is an inherited IRA protected from bankruptcy?
A non-spouse inherited IRA is not protected by the federal retirement funds exemption under Clark v. Rameker. State exemptions may offer protection in some jurisdictions.
Does a spouse’s inheritance belong to the other spouse?
Not automatically. Inheritance may remain separate property, but commingling, retitling, or using the money for jointly owned property can change the analysis. State marital property law controls.
Can an ex-spouse claim an inheritance during divorce?
An inheritance may be separate property, but it can become part of the marital estate if it is mixed with marital funds or used for shared property. State law and the timing of the inheritance matter.
Does a trust protect an inheritance from creditors?
It may. Protection depends on whether the trust is properly drafted, whether the beneficiary controls the trust, and whether the trustee has discretion over distributions.
Does a payable-on-death account avoid creditors?
It may avoid probate, but the funds can generally be exposed to the beneficiary’s creditors after the beneficiary receives them.
Can a beneficiary designation be changed after a diagnosis or lawsuit?
Sometimes, but changes made after a claim arises may be challenged. Legal advice is important before moving assets when creditor problems already exist.
Are life insurance proceeds protected from creditors?
Protection varies by state, policy structure, and beneficiary relationship. Direct proceeds paid to a beneficiary may become exposed after distribution.
Should an inherited IRA be transferred to a trust?
A trust may improve control and creditor protection, but it must be drafted to coordinate with retirement distribution and tax rules. This is not a do-it-yourself change.
Legal and Tax Disclaimer
This article is for general educational purposes only. It is not legal, tax, bankruptcy, estate-planning, or investment advice, and it does not create an attorney-client relationship. Creditor exemptions, probate rules, marital property laws, trust protections, and inherited account treatment vary by state and by personal circumstances. Consult a qualified attorney and tax professional before changing beneficiary designations, transferring assets, filing bankruptcy, or creating a trust.