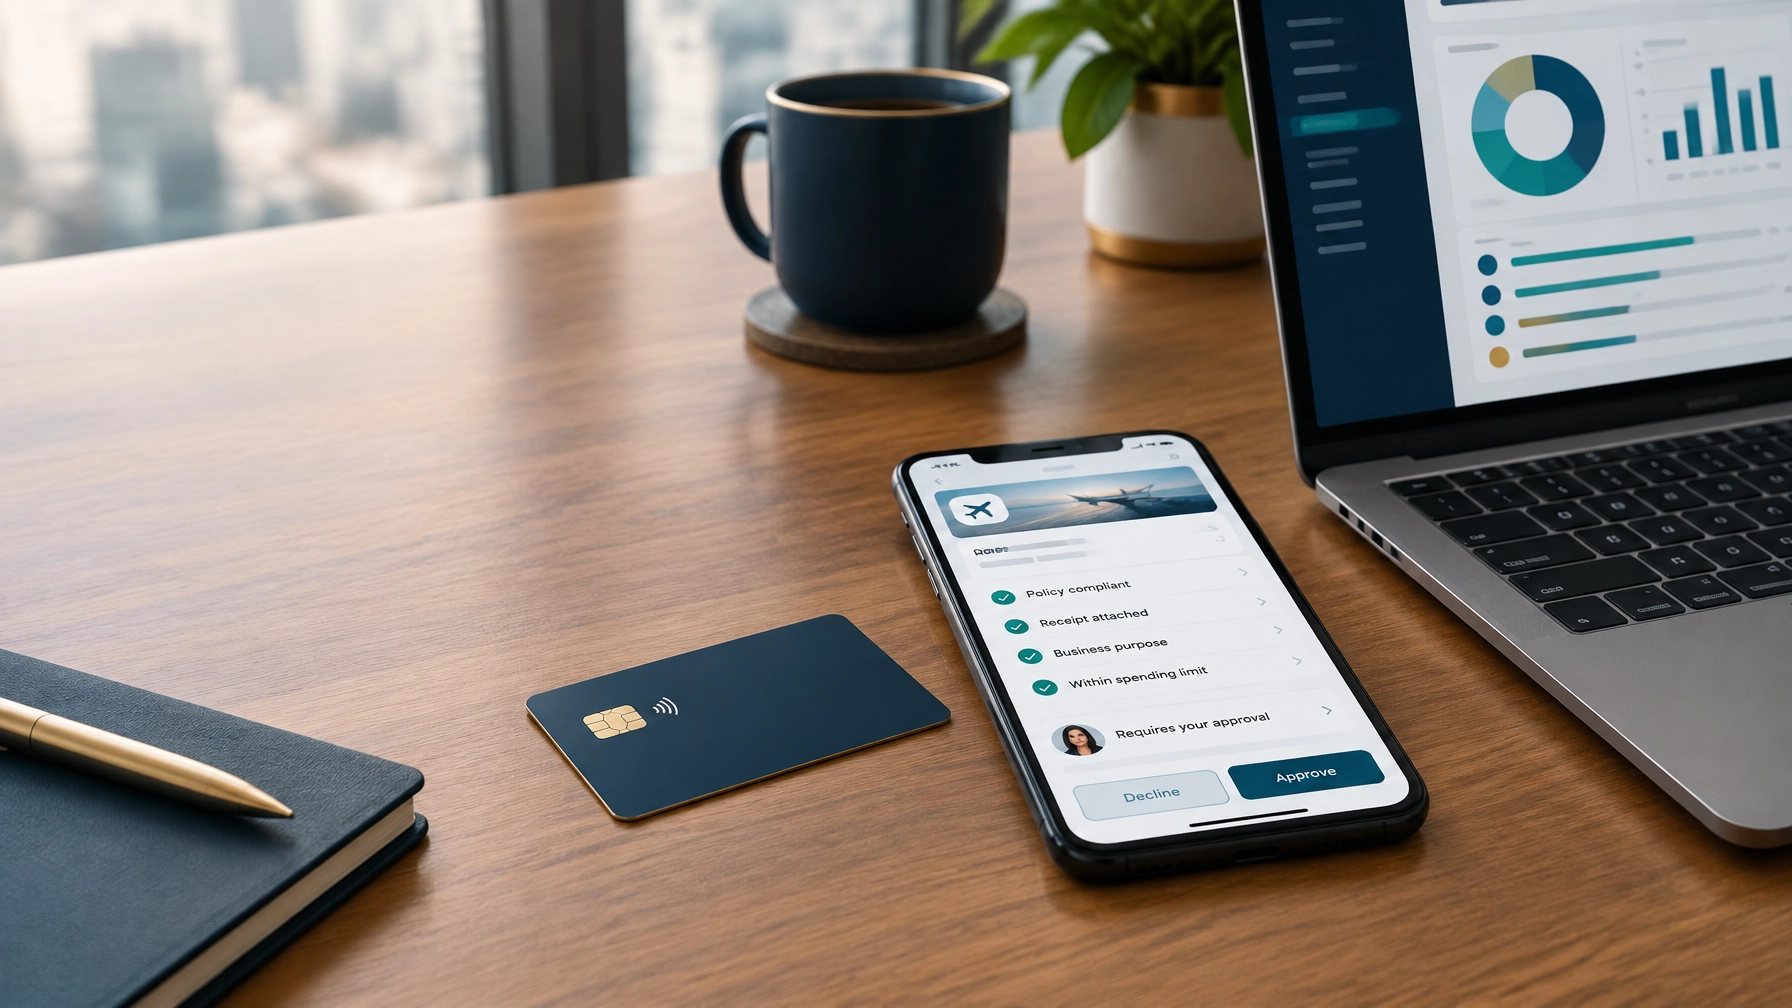
American Express announced the next generation of its Amex Corporate program. The offering combines Corporate Cashback Cards, expense management software, and a new Amex Expense mobile app.
The current app uses AI to recommend expense fields, verify receipts, and flag transactions that may violate company policy. American Express also plans to introduce additional agentic AI tools later in the fall, including:
- An expense agent that communicates with employees through SMS or Slack
- An insights agent that lets finance teams ask questions about company spending
- Automated reports and additional accounts payable workflows
This article covers a vendor-sponsored announcement from American Express. It is consumer and small-business education, not a recommendation of the card, program, or any other expense platform.
Why it matters
The most important change is not the card. It is the policy.
When software merely stores an expense policy, the policy remains a document. When an AI agent uses that policy to approve, route, or flag expenses, the policy becomes executable code.
That means a vague rule such as “reasonable client entertainment” may no longer be harmlessly vague. Software needs to determine what “reasonable” means, what evidence is required, who reviews an exception, and what happens next.
The key question for a small business is no longer only, “Is our expense policy fair?”
It is also, “Is our policy written precisely enough for software to apply consistently?”
In real life
Suppose your policy allows meals with clients but limits the cost to “a reasonable amount.” An employee submits a $185 dinner with a receipt and a client name. A human reviewer might approve it because the meeting supported a major account. An AI system may flag it because the policy does not define a dollar limit, required business purpose, or approval exception.
The flag is not proof of misconduct. It is evidence that the policy may be incomplete.
Watch
The benefit of automated expense management can be meaningful: less manual data entry, faster reconciliation, fewer late submissions, and better visibility into cash flow. But those gains depend on the quality of your rules, data controls, review process, and employee communication.
Source
American Express launches the next generation of Amex Corporate, via CPA Practice Advisor
Knowledge Snapshot
- American Express launched an integrated Corporate Cashback Card, expense management software, and Amex Expense app on September 30, 2026.
- The app already uses AI to recommend expense fields, review receipts, and flag possible policy violations.
- Planned expense agents will contact employees through SMS or Slack when information is missing.
- An insights agent is expected to answer finance questions and generate reports from company spending data.
- The central governance issue is policy precision. Automated enforcement can expose unclear or inconsistent rules.
- Acquisitions such as Hyper point to a broader industry trend: payment companies are combining card, expense, accounts payable, and AI capabilities in one system.
Quick Answer
Before enabling an AI expense agent, settle five questions:
- What does the policy actually say? Rewrite vague rules with clear dollar limits, dates, categories, receipt requirements, exceptions, and approval paths.
- What may the agent see and do? Confirm which transaction, receipt, employee, vendor, and accounting data it can access. Define whether it may suggest, submit, approve, reject, or only route expenses.
- Who reviews flags, and how quickly? Assign a person or team, set response times, and create an escalation process for urgent or disputed expenses.
- What happens to an employee who is flagged? A flag should begin a review, not automatically become a disciplinary finding.
- What audit trail exists? Preserve the policy version, data used, recommendation, human decision, and communication history.
If the vendor cannot answer these questions clearly, do not begin with full automation. Use a suggestion-only pilot instead.
Why Trust This Article
Ask The Money Coach focuses on practical financial education for individuals, families, and business owners. This analysis separates confirmed product announcements from broader questions that small businesses should ask before adopting financial technology.
The factual discussion is based on American Express announcements and reporting from American Banker, CPA Practice Advisor, The Paypers, and Business Travel News.
We do not assume that an advertised feature will fit every business. Pricing, eligibility, integrations, data terms, and controls should be confirmed directly in the current agreement and implementation documentation.
Editorial Perspective: The Policy Is the Product
American Express is presenting the new tools as a way to reduce administrative work. That is a reasonable benefit. Employees may spend less time reconstructing monthly expense reports, while finance teams may reconcile card purchases more quickly.
But automation does not remove management decisions. It moves them earlier in the process.
A business must decide what counts as compliant before an agent can classify an expense. It must decide who is accountable before the software routes a disputed charge. It must decide how much employee information is necessary before connecting receipts, messages, card transactions, and accounting records.
In other words, the expense policy becomes part of the product design.
1. Make the policy unambiguous
Before activating an agent, review every phrase that requires human judgment. Common examples include:
- “Reasonable and customary”
- “Pre-approved when possible”
- “Business-related travel”
- “Occasional client entertainment”“Use your best judgment”
- “Submit promptly”
These phrases may be understandable to a trusted manager, but they are difficult to apply consistently through software.
Replace them with operational rules. For example:
| Policy issue | Less precise | More precise |
|---|---|---|
| Meal limit | Reasonable client meal | Up to $125 per attendee, including tax and tip |
| Receipt timing | Submit promptly | Submit within 10 calendar days |
| Approval | Obtain approval when possible | Written approval required before purchases over $500 |
| Travel class | Standard travel | Economy airfare unless the trip exceeds six hours |
| Exceptions | Management may approve | The finance director may approve documented exceptions within five business days |
This is not about writing a longer policy. It is about removing avoidable ambiguity.
Also decide how the system should treat missing information. Should it remind the employee, hold the expense, route it to a manager, or allow submission with an explanation?
2. Define what the agent may see and do
Ask the vendor for a field-level data map. Do not settle for a general statement that data is protected.
Find out whether the tool can access:
- Merchant names and locations
- Transaction amounts and dates
- Receipts and receipt images
- Employee names, departments, and messages
- Business purposes, attendees, and project codes
- General ledger codes and cost centers
- Vendor invoices and accounts payable records
- Historical expense behavior
- Data from connected accounting or enterprise resource planning systems
Then separate visibility from authority.
An agent may need to see a transaction to categorize it. That does not mean it should be able to approve the expense or change a spending limit.
Use role-based permissions and begin with the least authority necessary. A sensible progression may be:
- Suggest categories and missing fields
- Ask the employee for confirmation
- Prepare the submission
- Route it to a human approver
- Automatically approve only low-risk expenses that meet clearly defined rules
Ask where the data is stored, how long it is retained, whether it is used to train models across customers, and how access is revoked when an employee leaves.
3. Assign responsibility for reviewing flags
A policy flag has operational consequences. It may delay reimbursement, hold up a client project, or create tension between an employee and manager.
Your business should identify:
- Who receives the flag
- How quickly the reviewer must respond
- What happens when the reviewer is unavailable
- Who handles disputes
- When finance, human resources, or legal staff should be involved
- Which expenses require immediate human review
A flagged transaction should not disappear into a dashboard.
Set a service standard, such as reviewing ordinary flags within two business days and urgent travel or payroll-related matters the same day. The exact standard depends on your business, but the responsibility should be explicit.
4. Decide what a flag means for the employee
An AI flag is a screening result, not a final judgment.
The system may be wrong because a merchant category is inaccurate, a receipt is incomplete, a policy exception was not included, or the employee has a legitimate business explanation.
Your written process should state:
- Employees can see why an expense was flagged
- Employees can add context or correct information
- A human reviews contested flags
- The company does not treat a first flag as proof of dishonesty
- Repeated violations are handled under a separate, documented process
- Managers may not use the tool selectively against particular employees
This matters for fairness, morale, and retention. A faster expense process is not a success if employees believe the system is monitoring them without a fair way to respond.
5. Preserve an audit trail
If a decision is challenged six months later, you should be able to reconstruct what happened.
The audit record should ideally show:
- The policy version in effect at the time
- The original transaction and receipt
- Information added by the employee
- The agent’s recommendation or reason for the flag
- The person who approved, changed, or rejected the expense
- Dates and times for each action
- Any override and the reason for it
- Relevant messages exchanged through the app, SMS, or Slack
Ask whether these records can be exported in a usable format. Also ask whether administrators can change policy rules without preserving the prior version.
An audit trail protects the business, but it also protects employees from unexplained decisions.
What the Acquisition Trend Means for Small Businesses
American Express has been building expense and AI capability through acquisitions, including its announced acquisition of Hyper. Industry coverage has also connected the company’s broader commercial strategy with expense-management capabilities obtained through Center.
For customers, consolidation can be convenient. One provider may connect the card, transaction feed, expense app, accounts payable workflow, and reporting system. Fewer disconnected tools can reduce duplicate data entry and integration costs.
The tradeoff is concentration risk.
When more financial data lives in one ecosystem, a business should ask:
- Can we export our records if we change providers?
- Which services stop working if we cancel the card?
- Are card, expense, and accounts payable data governed by the same retention terms?
- Can we use another accounting or enterprise resource planning system?
- How are vendor acquisitions integrated into security and privacy controls?
- What happens if a feature is discontinued?
The same questions apply when comparing other expense platforms, including Ramp, Brex, Expensify, and Zoho Expense. Features and pricing differ, but the governance questions are similar.
Practical Pre-Enablement Checklist
Before activating an AI expense agent, complete this review:
Policy
- Dollar limits are specific
- Merchant categories are defined
- Receipt rules and deadlines are clear
- Approval thresholds are documented
- Exceptions have an owner and deadline
- Policy versions are retained
Permissions
- Data fields available to the agent are documented
- Roles and administrator permissions are limited
- The agent’s ability to submit, approve, reject, or edit is clear
- Connected accounting systems are listed
- Retention and deletion terms are understood
People and process
- A reviewer owns each type of flag
- Review deadlines are written down
- Employees can explain or appeal a flag
- Managers know that a flag is not a finding of misconduct
- Staff receive training before launch
Testing
- The tool is tested with ordinary expenses
- Exceptions are tested
- Duplicate receipts and missing receipts are tested
- Policy changes are tested
- The business starts in suggestion-only mode if possible
Audit and cash flow
- Reports can be exported
- Agent actions are logged
- Overrides require a reason
- Reconciliation timing is measured
- The business tracks late submissions, review time, errors, and cash-flow visibility
ATMC Money Coach Box: The cheapest expense mistake is often the one prevented before the purchase. The safest automation is not the system that makes the most decisions. It is the system that makes the right decisions visible, reviewable, and easy to challenge.
What This Means for You
For a small business, AI expense management can reduce administrative drag. It may help employees submit expenses sooner, help finance teams close the books faster, and make spending patterns easier to see.
But speed should not be your only success measure.
Before enabling an agent, rewrite the policy, limit the agent’s authority, assign human reviewers, create a fair employee response process, and preserve the evidence behind every decision. Run a limited pilot and measure whether the tool actually improves cash-flow visibility and reconciliation time.
The central lesson is simple: when software enforces your expense rules, the policy is no longer just paperwork. It is operating infrastructure.
Make that infrastructure clear before you make it automatic.
For broader financial planning and business money guidance, explore the Ask The Money Coach financial education resources and affordable financial planning services.
FAQ
What is agentic expense management?
Agentic expense management uses software that can take steps within defined boundaries rather than merely display information. An expense agent may request a missing receipt, suggest a category, answer a policy question, prepare a submission, or route an expense for approval.
The agent’s authority depends on the business’s settings and the vendor’s capabilities. Ask whether the tool is suggestion-only or can submit, approve, reject, or change records.
Can an AI agent approve my employees’ expenses?
It may be able to approve expenses that meet preset rules, depending on the system and configuration. That does not mean every expense should be automatically approved.
Many businesses should begin with human approval or a limited low-risk workflow. Automatic approval is more appropriate when the policy is precise, the amount is modest, the data is reliable, and the audit trail is complete.
What data does AI expense software see?
It may see card transactions, merchant information, receipts, employee details, expense categories, business purposes, project codes, approval records, and connected accounting data.
The exact fields vary. Ask for a data inventory, retention schedule, list of subprocessors, model-training policy, access controls, and deletion process.
How do policy flags work?
The system compares expense information with configured rules. It may flag an amount above a limit, a merchant category that is restricted, a missing receipt, an overdue submission, or an incomplete business purpose.
A flag identifies a possible exception. It should not automatically be treated as evidence of employee wrongdoing.
Should small businesses use AI expense tools?
Some small businesses may benefit if they have frequent employee spending, recurring reimbursement delays, or limited finance staff. Others may find that a simple accounting workflow and clear card limits are sufficient.
Compare the expected time savings with subscription fees, implementation work, data risks, and the cost of reviewing false flags. Pilot the tool before committing to broad automation.
What should I check before enabling AI on our corporate cards?
Review five areas: policy clarity, agent permissions, human review, employee treatment, and audit records.
Also check data retention, integration with your accounting system, export capability, pricing, customer support, and what happens if you later move to a different card or expense platform.
AskTheMoneyCoach Staff is the collective byline for our editorial team. Founded by Lynnette Khalfani-Cox, The Money Coach®, and Earl Cox, AskTheMoneyCoach.com publishes practical, research-informed guidance on credit, debt, saving, consumer protection, and everyday money decisions. Our work follows the site’s editorial standards and helps readers understand their options and make informed choices.