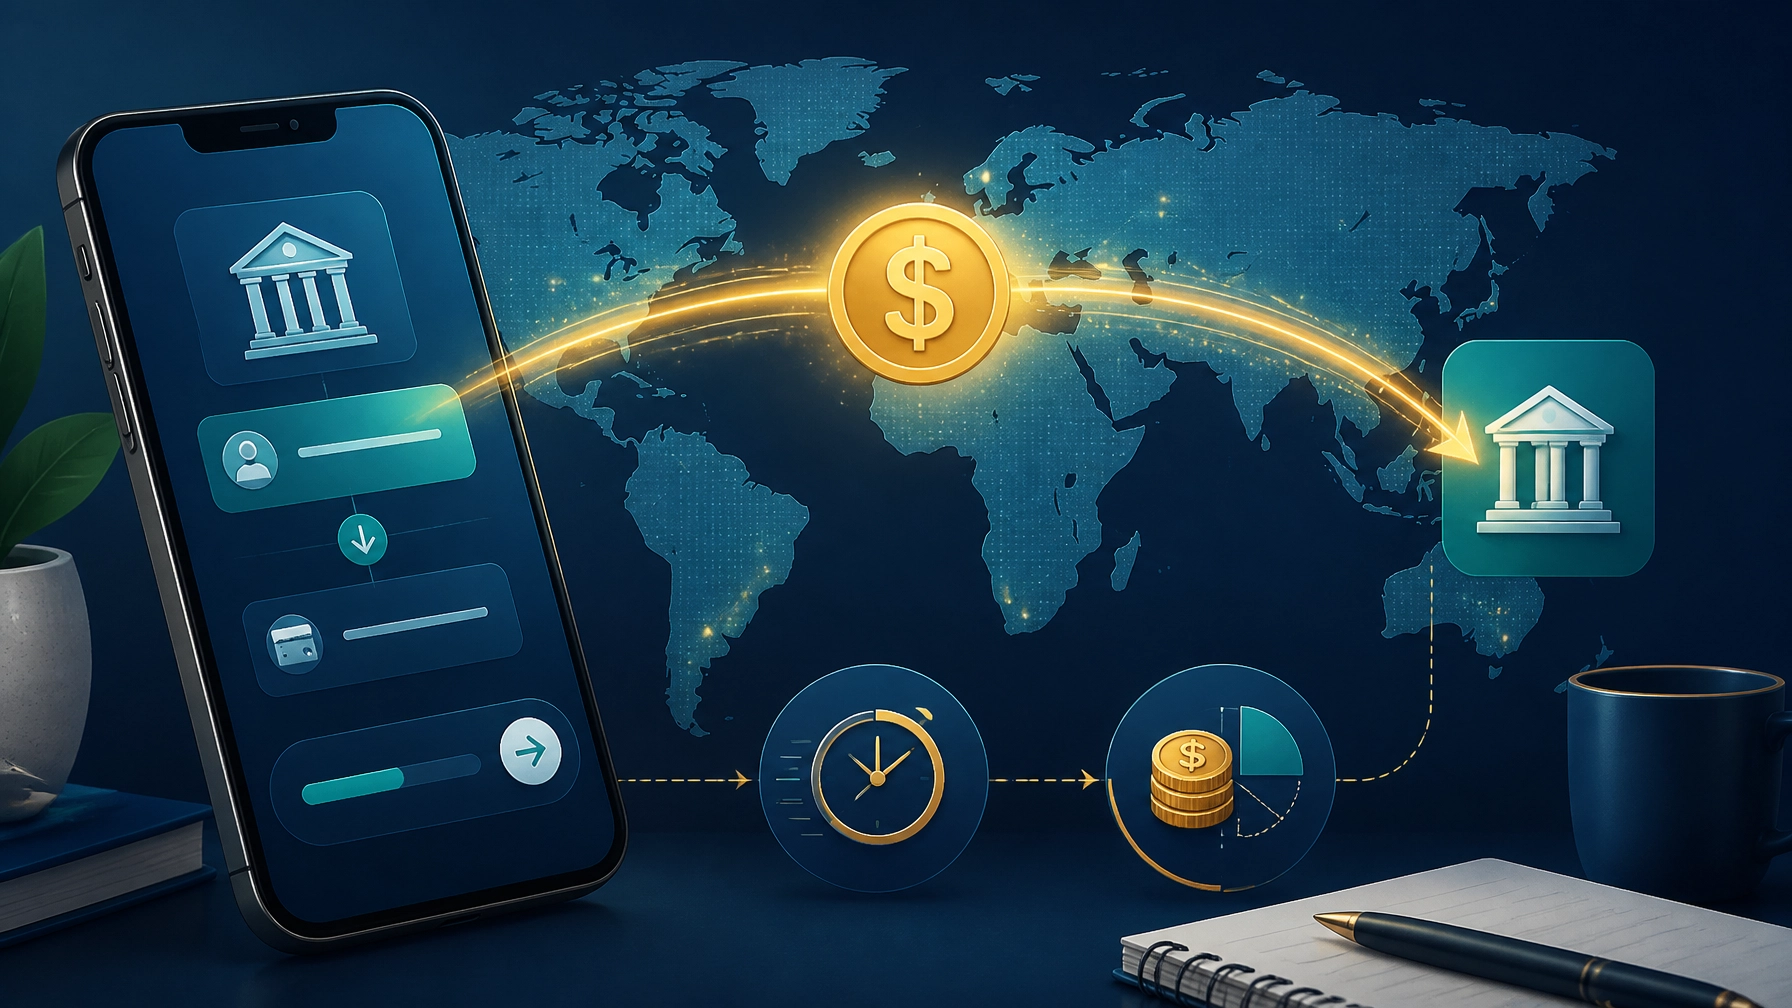
Santander announced that 21 international financial institutions have committed to establish a new company during the second half of 2026. The company would support the issuance of a stablecoin, beginning with a U.S. dollar version and potentially expanding into other G7 currencies, with the euro identified as a priority.
The participants include Bank of America, Citi, Goldman Sachs, Deutsche Bank, UBS, Santander, Wells Fargo, Capital One, PNC, TD Bank Group, and other major financial institutions.
The consortium says the product could serve wholesale, institutional, and retail markets. Planned uses include cross-border payments and digital asset settlements. The target launch is the first half of 2027, subject to the creation of the new company, regulatory requirements, and other closing conditions.
That is a significant development because stablecoins have largely been associated with non-bank digital asset companies. Major banks are now signaling that they do not want to leave digital payment rails, customer relationships, and related fee income entirely to firms such as Circle and Tether.
What Is a Stablecoin?
A stablecoin is a digital token designed to maintain a stable value against another asset, usually the U.S. dollar.
A dollar stablecoin is intended to remain worth approximately $1. The issuer typically holds reserve assets that support the tokens in circulation. Under the U.S. framework for payment stablecoins, those reserves may include bank deposits, short-term U.S. Treasury securities, or certain balances held at a Federal Reserve Bank.
Unlike a stock or a conventional cryptocurrency, a payment stablecoin is designed primarily for moving money rather than generating investment returns. The Federal Reserve describes payment stablecoins as digital assets intended to function as a means of payment while maintaining a one-to-one value relative to the dollar.
Still, a stablecoin is not identical to money in a checking account. The legal claim, reserve structure, redemption process, and consumer protections can be different.
That distinction will matter greatly if bank-backed stablecoins become part of everyday financial life.
Why Are Banks Joining the Stablecoin Market?
1. Banks want to control the payment rails
Payments are a major source of revenue and customer engagement for financial institutions. Every payment system has rules, infrastructure, compliance procedures, and opportunities to charge fees.
If businesses and consumers increasingly move money through privately operated digital tokens, banks could lose control of part of that activity. A bank consortium lets participating institutions build a payment system that connects with their existing customers and corporate relationships.
The financial institutions involved already operate large payment networks, correspondent banking relationships, treasury services, and consumer banking platforms. Their advantage is not simply issuing a token. It is distribution.
If customers can buy, hold, and redeem a stablecoin within a familiar bank relationship, adoption may be easier than opening an account with an unfamiliar crypto platform.
2. Regulatory clarity is improving
The consortium says it intends to comply with the U.S. GENIUS Act and the European Union’s Markets in Crypto-Assets Regulation, known as MiCA, where applicable.
These frameworks are designed to establish rules for payment stablecoin issuers, including reserve backing, authorization, supervision, disclosures, and consumer protections.
Regulatory clarity does not eliminate risk. It does, however, make it easier for banks to evaluate whether a product can be offered legally and how it should be managed.
Banks generally operate under extensive regulatory oversight. A clearer stablecoin framework gives them a path to participate without treating the entire market as an uncertain legal experiment.
3. Stablecoins could create new fee income
Banks may eventually earn revenue from:
- Converting dollars into stablecoins and redeeming tokens for dollars
- Processing payments
- Providing custody and wallet services
- Supporting business payment systems
- Facilitating foreign currency conversion
- Settling transactions involving digital assets
- Managing liquidity and reserve operations
The fees could be lower than traditional wire fees in some situations, particularly for cross-border transfers. But lower cost for the customer does not mean zero cost.
Stablecoin systems still require technology, compliance, customer support, fraud monitoring, foreign exchange services, and account access. Banks may reduce some intermediary costs while creating new pricing models around access and conversion.
What Could Change for Everyday Consumers?
Faster and more trackable payments
The clearest potential benefit is speed.
Traditional international payments may pass through multiple correspondent banks before reaching the recipient. Each intermediary can add processing time, compliance reviews, foreign exchange costs, and uncertainty about where the money is in the process.
A stablecoin could shorten that chain if both the sender and recipient, or their banks, have access to the same system. The Federal Reserve has noted that payment stablecoins could reduce some cross-border payment frictions by lowering reliance on intermediaries.
For a household, that could eventually mean faster transfers to family members abroad. For a small business, it could mean more predictable payments to international contractors or suppliers.
However, the stablecoin itself is only one part of the transaction. Converting dollars into another currency, withdrawing funds, and complying with local rules could still create delays and fees.
A new way to move money, not necessarily a better place to save it
The GENIUS Act prohibits payment stablecoin issuers from directly paying interest to token holders. That means a stablecoin would generally be designed as a payment instrument, not a savings account.
If you have $1,000 in a high-yield savings account, you may earn interest while keeping the money available for emergencies. If you convert that money into a non-interest-bearing stablecoin, you may give up that yield.
This creates an important household finance question:
Is the stablecoin helping you move money, or are you using it as a substitute for an interest-bearing deposit?
For routine payments, speed and convenience may matter. For money held over weeks or months, the loss of interest could become a meaningful opportunity cost.
More choices, but potentially more complexity
Consumers may eventually see several types of digital dollar products:
- Traditional bank deposits
- Bank-issued or bank-backed stablecoins
- Stablecoins issued by non-bank companies
- Tokenized deposits
- Payment app balances
- Card network transactions
- Real-time bank payments through systems such as FedNow
These products can look similar from a phone screen while carrying different legal and financial characteristics.
Stablecoin Versus Bank Deposit: Why the Difference Matters
A bank deposit is a liability of the bank. If it is held in an eligible account at an FDIC-insured bank, it generally receives automatic FDIC insurance coverage up to applicable limits.
The FDIC states that deposit insurance covers traditional deposit accounts such as checking accounts, savings accounts, money market deposit accounts, and certificates of deposit. It also states that crypto assets are not covered by FDIC deposit insurance.
A stablecoin held through a bank relationship should not automatically be treated as an FDIC-insured deposit. The final answer will depend on the product’s structure, the issuer, the account arrangement, and the applicable rules.
Consumers should ask:
- Is my balance a deposit account or a digital token?
- Is the balance directly covered by FDIC insurance?
- Who has the legal obligation to redeem the token?
- What reserve assets support the stablecoin?
- How quickly can I convert it back into dollars?
- Are there fees for buying, transferring, or redeeming it?
- What happens if the issuer experiences a technology failure or bankruptcy?
- Can the token be used outside the participating banks’ network?
The word “bank” in a product’s marketing does not answer all of these questions.
Will Everyone Need a Stablecoin?
No.
Most people will continue to manage everyday spending through checking accounts, debit cards, credit cards, payment apps, and ordinary bank transfers.
FedNow may provide participating financial institutions with a way to send instant payments within the United States. Cards remain widely accepted and familiar. Bank accounts provide direct access to deposits, bill payments, payroll, and consumer protections that differ from those attached to digital tokens.
A stablecoin may be useful for specific situations, such as:
- Cross-border payments
- Digital asset settlement
- Business-to-business payments
- Transfers that need to occur outside traditional banking hours
- Transactions involving programmable or blockchain-based systems
That does not make it the best option for rent, groceries, emergency savings, or a paycheck.
What Should Consumers Watch Before 2027?
The announcement describes a planned venture, not a finished product. The company name, final issuer structure, distribution model, pricing, supported wallets, and consumer eligibility have not been fully announced.
Before using any new stablecoin, watch for:
- Official disclosures from the issuing company and your bank
- Clear information about reserve assets
- Redemption terms and processing times
- FDIC insurance language
- Transaction and conversion fees
- Fraud protections and dispute procedures
- Tax reporting requirements
- Whether the token works across multiple institutions
- Whether your bank account is required to access it
Be especially cautious of messages claiming that you must “upgrade” your bank account by sending cryptocurrency or purchasing a stablecoin. New payment technology can create new opportunities for impersonation scams.
This development also does not mean consumers should buy cryptocurrency or move money into a digital wallet today. It is a change to monitor, not a personal finance instruction.
The Larger Shift in Digital Money
The 21-bank consortium represents a competitive shift in the digital money market.
Until now, stablecoins have been strongly associated with non-bank issuers and crypto-focused platforms. Large financial institutions are now attempting to combine digital tokens with bank-grade compliance, established distribution, and institutional risk management.
The result could be a more regulated stablecoin market with better integration into traditional finance. It could also create new questions about fees, data sharing, market concentration, deposit funding, and access.
The practical lesson for households is straightforward: understand the product before using it. A stablecoin may eventually make certain payments faster or easier, but it is not automatically a savings account, an investment, or a replacement for your existing bank.
For now, keep your focus on the fundamentals: maintain an emergency reserve, compare account fees, protect your login credentials, and use the payment method that provides the right combination of cost, convenience, security, and legal protection for the transaction.
Frequently Asked Questions
1. What is the 21-bank stablecoin?
It is a planned stablecoin venture backed by 21 international financial institutions. The group intends to establish a new company in the second half of 2026 and target a U.S. dollar-denominated stablecoin launch in the first half of 2027.
2. Which banks are involved in the stablecoin project?
Participants include Bank of America, Citi, Goldman Sachs, Deutsche Bank, UBS, Santander, Wells Fargo, Capital One, PNC, TD Bank Group, and other financial institutions listed in the Santander announcement.
3. Will the bank stablecoin be available to everyone?
The consortium says it is targeting wholesale, institutional, and retail applications. However, access rules, participating platforms, eligibility requirements, and consumer availability have not been finalized.
4. Will the stablecoin pay interest?
Payment stablecoins issued under the GENIUS Act framework generally cannot directly pay interest to holders. Consumers should not treat the proposed stablecoin as a high-yield savings account.
5. Will the stablecoin be covered by FDIC insurance?
Not automatically. FDIC insurance generally covers eligible deposits at FDIC-insured banks, while crypto assets are not insured. The specific protection for a stablecoin will depend on its legal structure and final disclosures.
6. Could stablecoins reduce international transfer fees?
They could reduce some intermediary costs by shortening payment chains. However, currency conversion, redemption, compliance, and platform fees may still apply.
7. Is a stablecoin safer than a cryptocurrency?
A regulated payment stablecoin may have stronger reserve, disclosure, and supervision requirements than many digital assets. That does not eliminate technology, operational, legal, fraud, or access risks.
8. How is a stablecoin different from a tokenized deposit?
A stablecoin is a digital token issued under a stablecoin framework. A tokenized deposit generally represents a deposit claim on a bank in digital form. The legal claims and protections can differ, even if both are designed to represent digital money.
9. Can I use a stablecoin to pay my rent or grocery bill?
Possibly in the future, but acceptance will depend on merchants, banks, payment platforms, and local rules. Ordinary bank transfers, debit cards, credit cards, and payment apps will remain available alternatives.
10. Should I move my savings into a stablecoin?
There is no general reason to do so. Compare interest, insurance, fees, access, and legal protections before moving money. A payment token may be useful for a specific transaction but unsuitable for emergency savings.
11. What should I do if someone asks me to buy a stablecoin to protect my bank account?
Stop and verify the request independently. Banks and government agencies do not normally require consumers to send money or purchase cryptocurrency to secure an account. Contact your financial institution through a trusted phone number or website.
12. When will the bank stablecoin launch?
The consortium is targeting the first half of 2027. That timeline could change because the new company, regulatory processes, technology, and product details are still being developed.
AskTheMoneyCoach Staff is the collective byline for our editorial team. Founded by Lynnette Khalfani-Cox, The Money Coach®, and Earl Cox, AskTheMoneyCoach.com publishes practical, research-informed guidance on credit, debt, saving, consumer protection, and everyday money decisions. Our work follows the site’s editorial standards and helps readers understand their options and make informed choices.