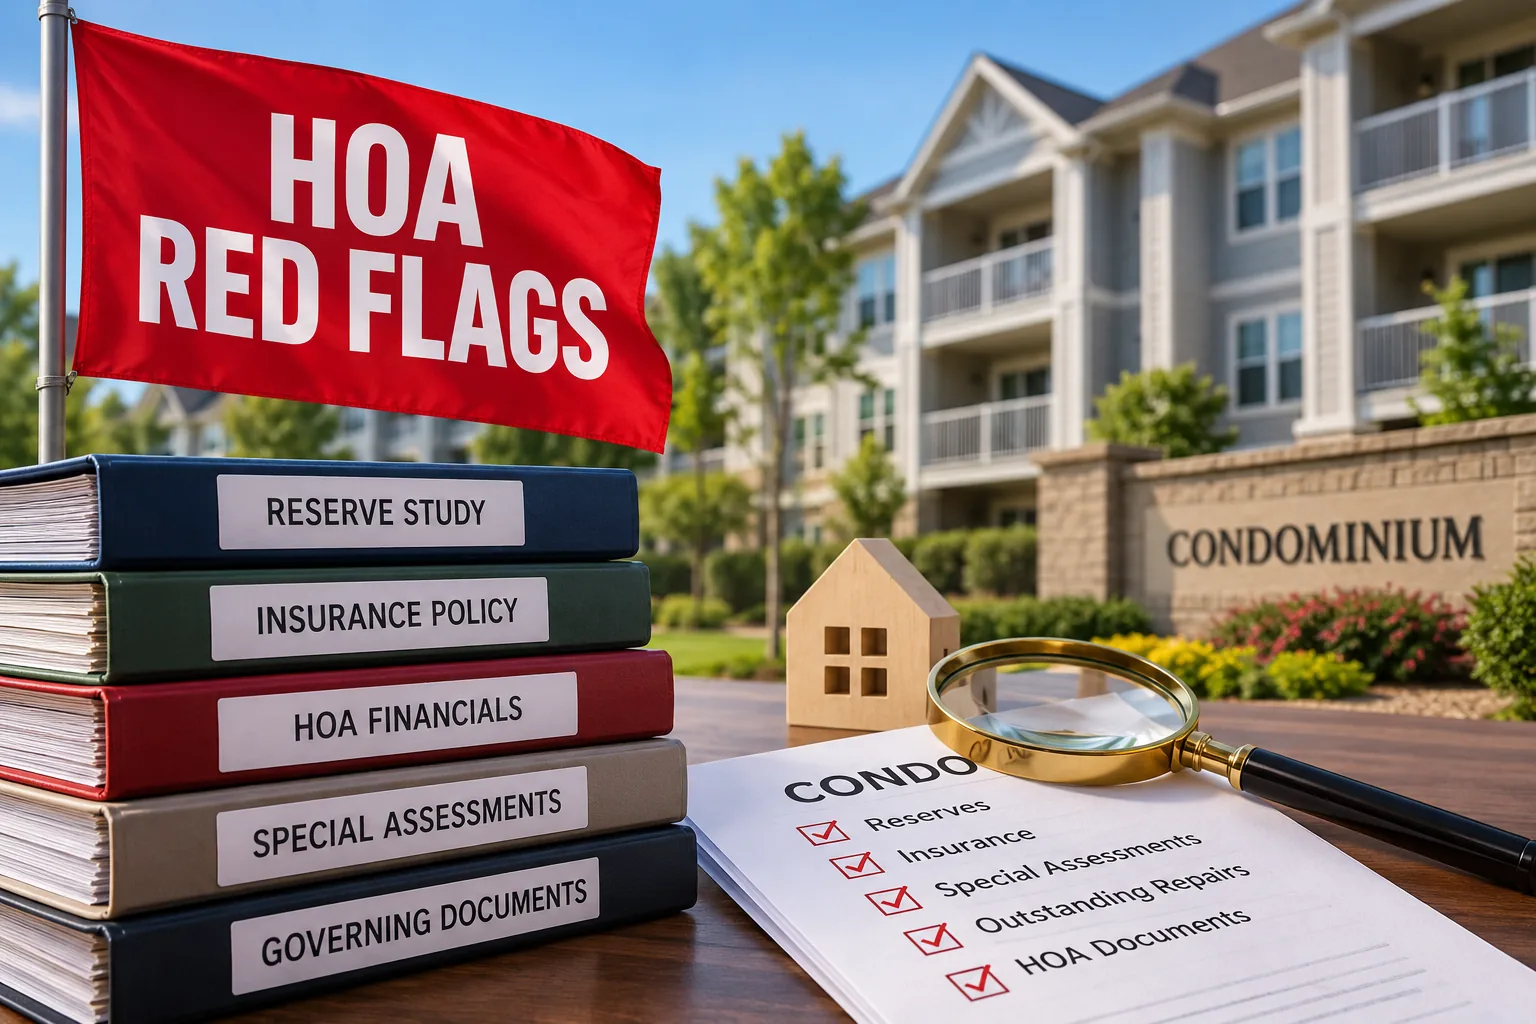
A recent Wall Street Journal story on spotting HOA risks before you buy a home stopped me in my tracks. I didn’t even need to read past the headline to feel a jolt of recognition.
My husband Earl and I lived through our own HOA fiasco not too long ago, when we sold two investment properties we owned in the same Raleigh, North Carolina condo community. What we went through taught me more about homeowners associations than any article ever could, and I want to share those lessons with you here.
For context: we owned two units in a 42 unit condo complex, one in each of the community’s two buildings. When it came time to sell both properties, we assumed the process would be straightforward. It was not.
Here’s what actually happened, and what I want every homebuyer and seller to know before dealing with an HOA.
1. An underfunded reserve fund can stall or sink your closing
Every HOA is supposed to maintain a “reserve fund,” which is essentially a savings account set aside for big ticket repairs like roofs, siding, and structural work. Based on some of the answers that came back on our lender’s questionnaire, our lender initially asked for a current reserve study before either sale could close.
That’s when we discovered how painfully slow this process can be, and honestly, how unprepared most HOAs are for this request.
One reserve study company wouldn’t even give us a price quote until we filled out an online form, and then told us a standard study would take 45 to 60 days, with a “rush” job still taking 30 to 45 days.
We also looked into a cheaper do it yourself reserve study kit, but it turned out those don’t hold up for mortgage lending purposes because they skip the site visit, the professional inspection, and the independent evaluation that federal lending guidelines actually require.
We ultimately found a workaround that satisfied our lender without commissioning a full study, so it never became mandatory for our closings. But the process was still a real eye opener. We learned that the vast majority of HOAs and condo buildings simply do not have an up to date reserve study on file, which means this exact scramble is waiting for a lot of sellers who have no idea it’s coming.
The takeaway for buyers: ask to see the HOA’s most recent reserve study before you make an offer, and find out when the next one is due. A reserve study that’s old, missing, or clearly underfunded relative to the building’s age and condition is a real warning sign, and it’s more common than you’d think.
The takeaway for sellers: don’t wait until you’re under contract to find out whether your HOA’s reserves and paperwork are in order. Ask the board now, while you still have time to fix problems calmly instead of during a closing deadline.
2. Missing insurance coverage can become your emergency, not just the HOA’s
This was maybe the most frustrating discovery of the entire process. Our lender required proof that the HOA’s master insurance policy included Law and Ordinance coverage, essentially protection that helps pay to rebuild to current building codes after a covered loss. Our HOA did not have this coverage.
When we asked around, we learned the board had been talking about adding this coverage for 12 years without ever actually doing it. Twelve years! Their inaction became our emergency, just days before our closing.
We initially offered to cover a full year of the added coverage if that’s what it took to get the deal done, and based on the premium estimates we were given, we were bracing to pay as much as $7,000 to $8,000.
It turned out we only needed to pay for the coverage on a prorated basis, covering the period through our closings and up to the policy’s renewal date. That ended up being $578, so getting it done for a fraction of what we’d braced for felt like a huge win.
Once our sales closed, the ongoing cost of maintaining that coverage going forward became the HOA’s responsibility, as it should be. Renewing and paying for adequate insurance year over year is on the association and its remaining owners, not on a departing seller.
The takeaway for buyers: ask specifically whether the HOA’s master policy includes Law and Ordinance coverage, and ask when it was last reviewed. Don’t assume a policy is complete just because a policy exists.
The takeaway for sellers: get a copy of your HOA’s current master insurance policy well before you list. If there’s a gap, you want to know about it on your own timeline, not your buyer’s lender’s timeline.
3. Sloppy HOA paperwork can derail a deal that has nothing wrong with it
Our lenders required a Condominium Project Questionnaire from the HOA’s management company. When it finally came back, it was riddled with errors: incorrect building counts, contradictory answers about multi unit ownership, and most alarming, a “yes” answer to a question about outstanding critical repairs. That single incorrect answer triggered additional scrutiny from the lender’s project review team and threatened to delay our closing.
The truth was our HOA had completed a comprehensive capital improvement project a couple of years earlier addressing balconies, roofing, and major building components, and that work was fully completed and fully funded. There were no outstanding critical repairs.
But someone at the management company checked the wrong box, and it took a very specific, well documented correction to get it fixed before closing.
The takeaway for buyers and sellers alike: whoever is filling out lender paperwork on the HOA’s behalf, whether that’s a management company or a volunteer board member, can make mistakes that have nothing to do with the actual condition of the property. Review these forms carefully, and don’t assume that a scary sounding answer is accurate just because it came from the HOA.
4. Special assessments and capital projects need to be understood, not just disclosed
Our HOA had gone through a real, and expensive, capital improvement cycle involving balcony repairs, roofing, and other major building components, funded partly through special assessments.
That history mattered a great deal during our closings, because federal lending guidelines actually treat special assessment funded repairs differently than unfunded critical repairs. Understanding that distinction, and being able to explain it clearly, made the difference between a delayed closing and a smooth one.
The takeaway for everyone: don’t just ask whether an HOA has had special assessments. Ask what they were for, whether the work is complete, and whether it was fully funded. The difference between a past special assessment for planned capital work and an unresolved, unfunded repair is not just a technicality. It can directly affect whether a lender will approve financing on the property.
The bigger lessons
HOAs can offer real value, shared maintenance, amenities, and a sense of community. But an HOA is also a business, run mostly by volunteers, and like any business it can be well managed or poorly managed.
Earl and I learned that the hard way, not because our HOA was fraudulent or malicious, just chronically slow to act on things that mattered. Thankfully, one board member in particular went above and beyond to help us get things resolved in time, and that reminded me how valuable it is to have even one responsive, cooperative contact within your HOA when things get tight.
If you’re buying into an HOA, do your homework before you’re under contract. If you’re selling, get ahead of these issues before a lender’s deadline forces your hand.
Either way, ask for the documents, read them closely, and don’t be afraid to push for answers. It’s your money, and often your closing date, on the line.
FAQ: 4 HOA Red Flags I Learned the Hard Way
What is an HOA reserve fund?
An HOA reserve fund is money set aside for major future repairs and replacements, such as roofs, siding, balconies, pavement, elevators, and other shared building components. Buyers should review whether reserves appear adequate for the age and condition of the property.
What is an HOA reserve study?
A reserve study evaluates the condition and expected life of major community assets and estimates how much money the HOA should save to pay for future repairs and replacements. Mortgage lenders may sometimes request reserve information when evaluating a condo project.
Can an underfunded HOA affect a mortgage approval?
Yes. A lender reviewing a condominium project may look at the HOA’s reserves, insurance, special assessments, deferred maintenance, and critical repairs. Problems in any of these areas can trigger additional review, delay financing, or make a property harder to finance.
What HOA documents should buyers review before purchasing a condo?
Buyers should consider reviewing the HOA’s budget, reserve study, financial statements, master insurance policy, meeting minutes, governing documents, current or planned special assessments, and information about major repairs or capital projects. Your lender may also require a condominium project questionnaire.
What is Law and Ordinance coverage in an HOA insurance policy?
Law and Ordinance coverage can help pay additional costs associated with rebuilding or repairing a property to comply with current building codes after a covered loss. Condo buyers and sellers should not assume this coverage is included in an HOA’s master insurance policy.
Can mistakes on an HOA questionnaire delay a home closing?
Yes. Incorrect answers on a condominium project questionnaire can trigger additional lender review even when there is no actual problem with the property. Buyers and sellers should review important HOA documentation carefully and request corrections when information is inaccurate.
Are special assessments always a red flag?
No. A special assessment is not automatically a sign of financial trouble. What matters is why the assessment was imposed, whether the related work has been completed, how it was funded, and whether additional costs remain. A completed and fully funded capital project is very different from an unresolved repair with no funding plan.
What should sellers check with their HOA before listing a condo?
Before listing, sellers should consider obtaining the HOA’s current budget, insurance policy, reserve information, recent meeting minutes, details about special assessments, and documentation concerning major repairs. Identifying problems before accepting an offer can reduce surprises during the lender’s condo review.
AskTheMoneyCoach Staff is the collective byline for our editorial team. Founded by Lynnette Khalfani-Cox, The Money Coach®, and Earl Cox, AskTheMoneyCoach.com publishes practical, research-informed guidance on credit, debt, saving, consumer protection, and everyday money decisions. Our work follows the site’s editorial standards and helps readers understand their options and make informed choices.