Credit card rewards can feel like a bonus for spending you were already planning to do. Cash back, airline miles, hotel points, and sign-up offers are attractive because they appear to reduce the cost of everyday purchases.
But rewards are not free.
A recent study from researchers affiliated with Harvard, Northwestern, Stanford, and Georgia State estimates that the credit card payment system shifts billions of dollars each year from cash and debit users to credit card users. The finding raises an important consumer question: Who really pays for your credit card rewards?
The answer is more complicated than “the bank.” Rewards are funded through a combination of merchant fees, consumer prices, annual fees, and interest charges. The financial impact also depends heavily on how you pay your balance.
How credit card rewards are funded
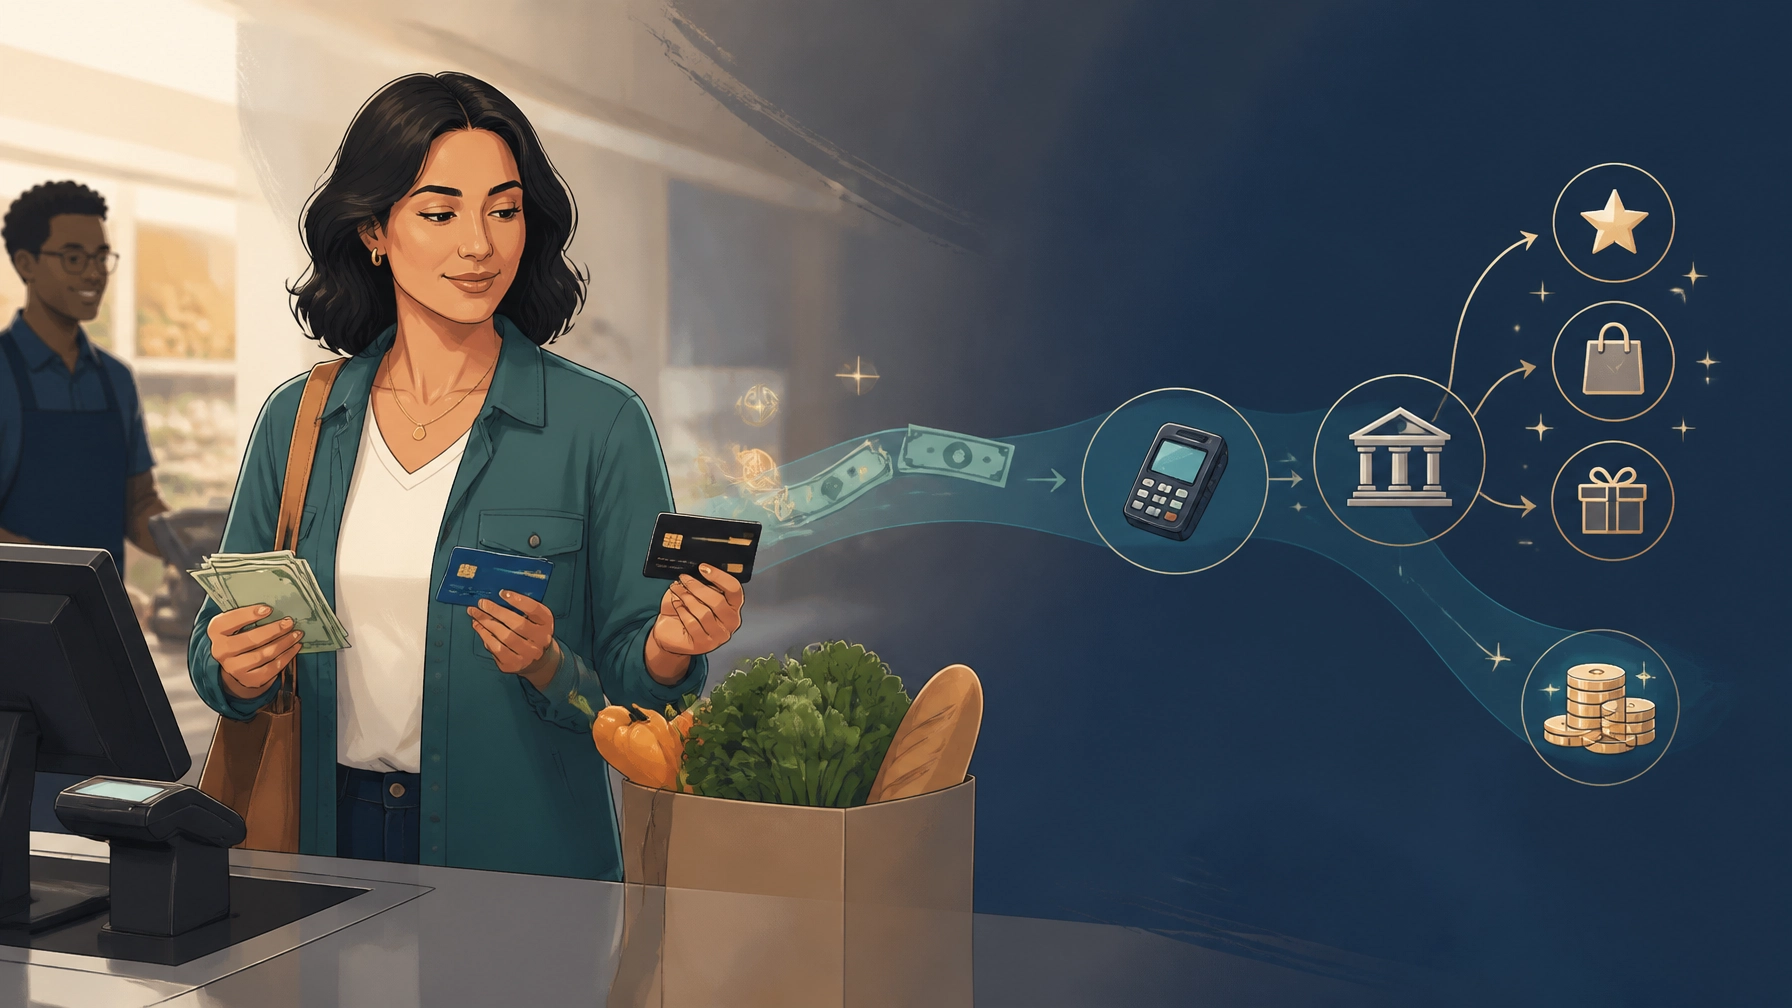
When you pay with a credit card, the merchant usually pays a fee to accept that transaction. The fee is part of the broader cost of card processing.
One portion is called an interchange fee. In a typical transaction, the merchant’s bank sends this portion to the bank that issued your credit card. The card network, such as Visa or Mastercard, establishes the relevant fee schedule.
The merchant does not usually send you a separate bill for interchange. Instead, the cost becomes part of the merchant’s operating expenses. Businesses may respond by:
- Raising prices across products
- Accepting lower profit margins
- Negotiating different fees with payment processors
- Adding a surcharge or offering a cash discount
Most merchants still charge one posted price whether you pay with cash, debit, or credit. That pricing structure is central to the current debate.
What the Harvard and NBER research found
The NBER Working Paper 35067, “Who Pays for Payments?”, was written by Mark L. Egan, Gregor Matvos, Amit Seru, Lulu Wang, and Vincent Yao. Harvard Business School’s Working Knowledge article also explains the research for a general audience.
The researchers analyzed payment data from roughly one million merchants, along with additional data that captured cash transactions. Their central argument is straightforward:
- Credit card issuers receive interchange revenue from merchants.
- That revenue helps fund rewards and other card benefits.
- Merchants often spread payment costs across all customers.
- Cash and debit users pay the same prices but receive fewer rewards.
- Higher-income households are more likely to use premium rewards cards and capture more of the benefits.
The study estimates that interchange fees transfer approximately $30 billion annually from cash and debit users to credit card users. It also estimates a roughly $9.2 billion annual transfer from households earning under $150,000 to households earning more than $150,000.
Those figures are estimates, not charges appearing on individual shopping receipts. They describe the researchers’ calculation of how benefits and costs are distributed across large groups of consumers.
The research also found that consumer behavior and merchant differences reduce the estimated transfer by about 25 percent. Cash users, debit users, and premium credit card users do not all shop at the same places. Large retailers and grocery chains may also negotiate lower interchange rates than smaller businesses.
That makes the real-world effect less uniform than the headline number suggests.
Why rewards often favor wealthier households
Rewards cards tend to benefit people who can do three things consistently:
- Qualify for attractive cards
- Spend enough to earn meaningful rewards
- Pay the statement balance in full every month
Higher-income households are more likely to meet all three conditions. They may also spend more on travel, dining, entertainment, and other categories that earn elevated rewards.
A household with strong cash flow can charge $4,000 per month, earn rewards, and pay the entire balance before interest accrues. A household with limited cash flow may use the same card to cover an emergency, carry a balance, and pay interest that quickly exceeds the value of the rewards.
For example, suppose a card provides 2% cash back:
- Monthly spending: $2,000
- Annual spending: $24,000
- Annual rewards: $480
That $480 benefit disappears quickly if the cardholder pays significant interest or an annual fee. Even without interest, the cardholder must spend money to earn the reward. Spending more to “maximize points” is not a savings strategy.
The important pushback to the research
The Harvard and NBER findings have drawn criticism. In a Forbes analysis, Ron Shevlin disputed the idea that the research proves a literal transfer of money from low-income consumers to wealthy consumers.
The counterargument focuses on several issues:
- Merchants may not pass every interchange cost directly into prices.
- Prices are affected by labor, rent, supplies, competition, and many other expenses.
- Points and miles do not have one universal cash value.
- Some rewards are never redeemed.
- Lower-income consumers may not shop at merchants where premium card spending is concentrated.
- Surcharges and cash discounts can make payment costs more transparent.
These are legitimate limitations to consider. A working paper provides research findings, but it does not settle every question about consumer welfare. The study measures the distribution of payment costs and rewards. It does not fully measure the value of credit access, fraud protections, convenience, credit building, or rewards that consumers fail to redeem.
The fairest conclusion is this: the rewards system appears to distribute benefits unevenly, but the exact size and practical effect of that imbalance remain open to debate.
What this means for everyday shoppers
You do not need to stop using credit cards because rewards may be subsidized through merchant pricing. Credit cards can provide useful protections, payment flexibility, and credit-building opportunities.
The key is to evaluate the card based on your complete financial picture.
A rewards card may help if you:
- Pay the full statement balance every month
- Avoid late fees and penalty charges
- Use the card for planned purchases
- Redeem rewards regularly
- Keep annual fees lower than the value of benefits
- Avoid spending more just to earn points
A rewards card may hurt if you:
- Carry a balance from month to month
- Use credit for routine expenses you cannot afford
- Chase sign-up bonuses with unnecessary purchases
- Forget about annual fees or redemption restrictions
- Treat rewards as a reason to upgrade your lifestyle
- Have difficulty keeping payment due dates organized
Your personal interest rate matters more than the advertised rewards rate. A card that earns 2% cash back but charges interest on an unpaid balance can become expensive very quickly.
Should you pay with cash, debit, or credit?
There is no single best payment method for every person or purchase.
| Payment method | Potential advantage | Main risk or limitation |
|---|---|---|
| Cash | Helps limit spending and avoids revolving debt | No rewards and less convenience for online purchases |
| Debit | Uses money already in your bank account | Usually provides fewer rewards and can create overdraft risk |
| Credit | May offer rewards, fraud protections, and credit-building | Interest and fees can outweigh rewards |
A practical approach is to match the payment method to your cash flow.
If you are working to control spending or pay down debt, debit or cash may provide useful guardrails. If you have stable income, a reliable budget, and a history of paying in full, a no-annual-fee cash-back card may be reasonable.
The goal is not to capture every available point. The goal is to improve your net financial position.
A simple rewards card checkup
Review your card once or twice a year and calculate:
- Total rewards redeemed
- Annual fees
- Interest paid
- Late fees and other charges
- Extra spending caused by rewards promotions
- The value of unused points or benefits
Use this formula:
Net card value = rewards redeemed + benefits used – annual fees – interest – other fees
If the result is negative, the card is not rewarding you, regardless of its marketing.
For broader budgeting support, see Ask The Money Coach’s guides on taking control of your finances and how to start saving money. You can also read about digital payment trends and how payment choices are changing.
The bottom line
Credit card rewards are funded through a complex system. Merchants pay interchange fees, those costs may be reflected in prices, and card issuers use revenue from multiple sources to support rewards programs.
The Harvard and NBER research suggests that cash and debit users may help finance rewards captured disproportionately by higher-income credit card users. Critics reasonably question how much of that cost reaches retail prices and whether “wealth transfer” is the best description.
For your household, the most important question is more personal: Do your rewards exceed the interest, fees, and extra spending associated with the card?
Use credit strategically, track the complete cost, and never let points persuade you to spend money you would otherwise keep.
Frequently Asked Questions
Are credit card rewards really free?
No. Rewards are funded through a combination of interchange revenue, interest charges, annual fees, and other card income. Merchants may also reflect payment costs in their prices.
Do cash users pay more than credit card users?
They may pay the same posted prices while receiving none of the rewards. The NBER study argues that this can create an indirect subsidy from cash and debit users to rewards card users.
Do debit card users subsidize credit card rewards?
According to the research, regulated debit users receive relatively few rewards while bearing a meaningful share of fee-related costs passed through merchant pricing.
Is it wrong to use a rewards credit card?
No. A rewards card can be useful when you pay the balance in full, avoid fees, and use it for planned purchases. The problem is paying interest or overspending to earn rewards.
What is an interchange fee?
An interchange fee is the portion of a card-processing fee that generally flows from the merchant’s bank to the cardholder’s bank. It helps support the cost of issuing and operating payment cards.
Why do premium credit cards have higher rewards?
Premium cards often charge merchants higher interchange fees and may also collect annual fees. Issuers use those revenue sources to support richer rewards and benefits.
Are cash-back cards better than travel cards?
Not automatically. Cash-back cards are usually easier to value, while travel cards may provide greater value to consumers who can use points strategically. Compare the annual fee, redemption rules, and your actual spending.
Can merchants charge more for credit card purchases?
Some merchants impose credit card surcharges or offer discounts for cash, subject to applicable laws, network rules, and disclosure requirements. These practices are not universal.
Should I use a debit card instead of a credit card?
Debit may be appropriate if you want to limit spending to money already in your account. Credit may offer stronger purchase protections and credit-building benefits. Your cash flow and spending habits should guide the choice.
How can I tell whether my rewards card is worth keeping?
Add your redeemed rewards and benefits, then subtract annual fees, interest, and other charges. If the result is not positive, consider a less expensive card or a different payment strategy.

Lynnette Khalfani-Cox, The Money Coach, is a renowned financial expert, author, speaker, and media personality, empowering people to achieve financial success. Visit her personal website at https://lynnettekhalfanicox.com.