When credit card balances rise, debt consolidation can sound like a clean reset: one payment, one due date, and possibly a lower interest rate.
That relief can be real. But consolidation does not erase debt. It changes the structure of the debt, usually by replacing several revolving balances with one loan, balance transfer card, home equity product, or debt management plan.
The central question is not simply, “Will my monthly payment go down?”
It is:
Will this plan reduce my total cost, give me a realistic payoff date, and prevent me from rebuilding the balances?
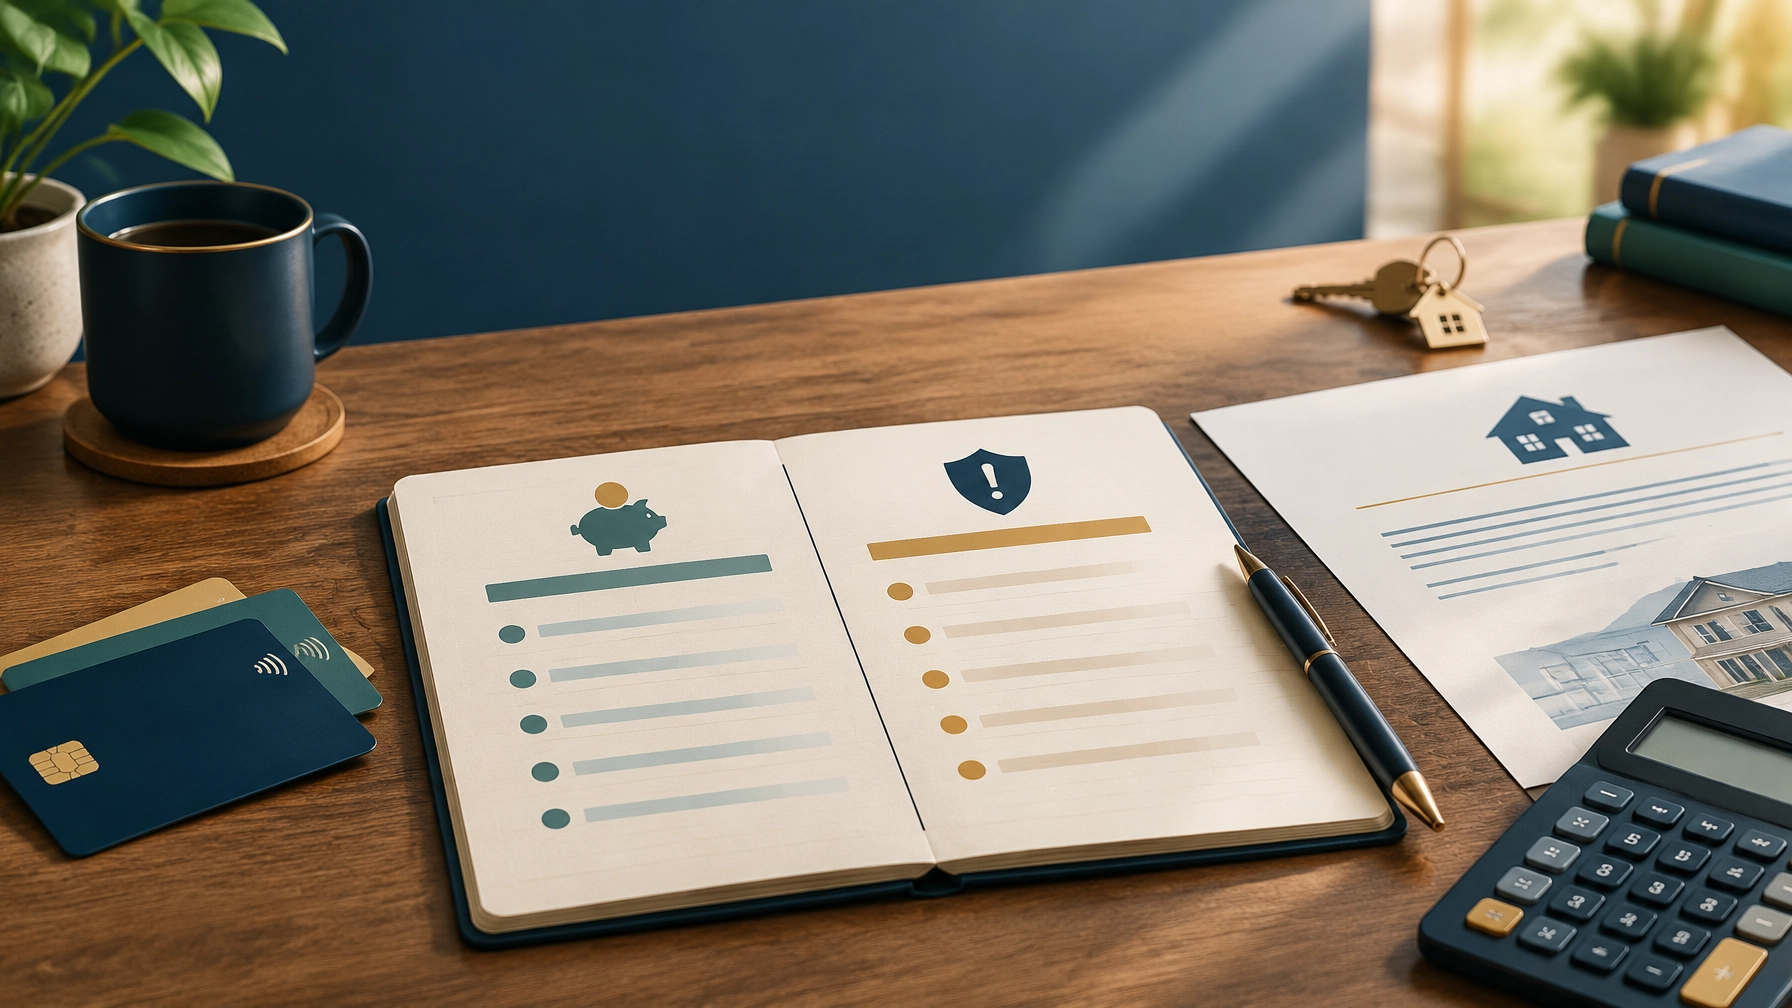
That is the purpose of the consolidation ledger. On one side, record what the new arrangement could save. On the other, record what it could expose you to.
Knowledge Snapshot
- U.S. credit card debt reached $1.263 trillion in the second quarter of 2026, up $21 billion from the previous quarter, according to the Federal Reserve Bank of New York.
- The average interest rate on all credit card accounts at commercial banks was 20.94% in the second quarter of 2026, compared with 15.13% in the same period of 2022, according to Federal Reserve data reported by ABC News.
- LendingTree found that a borrower with a credit score of 760 or higher could save about $1,750 by moving $10,000 of card debt into a personal loan, under a specific set of assumptions.
- Consolidation can lower interest costs, but it does not change the spending behavior that created the balance.
- Using home equity can convert unsecured credit card debt into debt secured by your home.
Quick Answer: Is Debt Consolidation Worth It?
Debt consolidation may be worth it when you qualify for a meaningfully lower rate, the fees are modest, the new term is not unnecessarily long, and you have a plan to stop adding card debt.
It may not be worth it when:
- The new APR is close to or higher than your current weighted average APR.
- Origination or balance transfer fees consume most of the projected savings.
- The payment is lower only because the debt has been stretched over a much longer period.
- You are using home equity without understanding the risk to your house.
- You are likely to use the paid-off credit cards again.
The last point is the trap that receives too little attention. Consolidation changes the interest rate. It does not change the spending pattern.
Why Trust This Article
This article combines current household debt data from the New York Fed, reporting from ABC News, and LendingTree’s personal loan analysis. The goal is not to promote a particular lender or debt product. It is to help you compare the full cost and risk of each option.
The LendingTree figures are especially useful because they show how much the result depends on creditworthiness, APR, term, and payment assumptions. Those figures are not a promise of what you will qualify for. They are a model for how to evaluate your own offer.
Editorial Perspective: Treat Consolidation Like a Ledger, Not a Lifeline
A consolidation offer often emphasizes the new monthly payment. That number matters for cash flow, but it is not the whole decision.
A lower payment can help a household stay current. It can also conceal a longer repayment period and a higher total cost.
Before signing, create two columns:
| What consolidation could save | What consolidation could risk |
|---|---|
| Lower APR | Cards become available for new charges |
| One predictable payment | Origination or balance transfer fees |
| Fixed payoff date | Longer term and more total interest |
| Less interest accruing each month | Less flexibility if income falls |
| Faster payoff when the payment stays high | Home becomes collateral if equity is used |
The ledger forces you to evaluate both sides. It also makes one truth impossible to ignore: the debt only stays consolidated if you do not refill the cards.
The Math: When the Interest Savings Are Real
The first calculation is your current weighted average APR. If you have three cards, do not compare a new loan with only the highest or lowest card rate.
For each card:
- Multiply the balance by its APR.
- Add those interest-weighted amounts together.
- Divide by your total card balances.
For example, a household with $4,000 at 18%, $3,000 at 24%, and $3,000 at 27% has a weighted average APR of about 22.8%. A new loan at 18% may be an improvement, but the savings will be smaller than if the borrower qualified for 12%.
Next, compare the complete repayment path:
- Current total balance
- Current monthly payment
- Current estimated payoff date
- Current total interest
- New APR
- New monthly payment
- New term
- Origination or transfer fees
- New total interest
- Net savings after fees
LendingTree’s 2026 analysis provides a useful example. For a borrower with a credit score of 760 or higher, the analysis compared $10,000 of credit card debt at 20.18% with a 36-month personal loan at 13.34%.
Under a fixed monthly payment of $339:
| Credit card | Personal loan | |
|---|---|---|
| APR | 20.18% | 13.34% |
| Monthly payment | $339 | $339 |
| Total interest | $3,939 | $2,189 |
| Payoff time | 42 months | 36 months |
The modeled difference was approximately $1,750 in interest and six months of repayment time.
That is a strong result, but it depends on the borrower receiving the assumed rate and maintaining the same payment discipline. LendingTree also found smaller savings for borrowers with lower credit scores because the gap between personal loan rates and card rates narrowed.
The lesson is important: consolidation is not automatically profitable. The rate spread does the work.
The Four-Question Qualification Test
Before applying, answer these four questions in writing.
1. What rate do I actually qualify for?
Do not rely on an advertised “as low as” rate. Use prequalification when available and ask whether the inquiry involves a soft or hard credit check.
Compare the offered APR with your weighted average card APR. A personal loan at 21% may not be useful if your existing cards average 20.5%.
Also confirm whether the rate is fixed. A fixed rate creates a more predictable payment. A variable rate can change and make budgeting more difficult.
2. What is the fee?
Possible costs include:
- Personal loan origination fees
- Balance transfer fees
- Application or documentation fees
- Annual fees on a balance transfer card
- Prepayment penalties, if any
- Closing costs for certain home equity products
ABC News reported that balance transfer fees commonly range from 3% to 5% of the transferred amount. A 4% fee on $10,000 would be $400 before any interest savings.
Subtract every fee from the projected interest savings. If you expect to save $700 but pay $600 in fees, the decision deserves much more scrutiny than an offer showing $700 of gross savings.
3. What is the new term?
A lower payment is not necessarily a lower cost.
Suppose your current payment plan would retire the debt in three years, but the consolidation loan lasts five years. The new payment may feel more manageable, yet the longer term can reduce or eliminate the interest savings.
A reasonable consolidation plan should have a clear payoff date. If you can afford the old payment, consider continuing to pay that amount on the new loan. The lower APR can then direct more of each payment toward principal.
4. What stops me from running the cards back up?
This is the most important question.
Consider practical safeguards:
- Remove saved card numbers from shopping accounts.
- Put the paid-off cards away or close accounts that are not needed.
- Keep one card available only for a defined emergency, if appropriate.
- Build a small cash buffer so an unexpected expense does not go straight back on plastic.
- Track cash flow weekly during the first several months.
- Set a rule that new card purchases must be paid in full each month.
If the consolidation loan pays off $10,000 in card debt and you later add $6,000 back to those cards, you have not solved the problem. You now have a loan payment and new revolving debt.
Compare the Main Consolidation Options
Fixed-rate personal loan
A personal loan can replace multiple card balances with one installment payment. It may be attractive when your credit and income qualify you for a substantially lower fixed APR.
The main risks are fees, a long term, and the temptation to treat newly available card credit as extra cash.
0% balance transfer card
A balance transfer card may offer an introductory period with no interest on transferred balances. ABC News reported that some offers provide an interest-free period lasting as long as 15 months, though terms vary.
Check:
- Length of the promotional period
- Balance transfer fee
- APR after the promotion ends
- Whether new purchases receive the same promotional treatment
- Required monthly payment
- What happens if you miss a payment
A 0% offer only works if you can pay the balance before the promotional period ends or have a clear plan for the remaining balance. Divide the transferred balance, plus the transfer fee, by the number of promotional months. That is roughly the monthly amount required to finish on time, before considering other charges.
Home equity loan or HELOC
Home equity may offer a lower rate than credit cards, but it changes the nature of the risk.
Credit card debt is generally unsecured. A home equity loan or HELOC is secured by your home. If you cannot repay, foreclosure risk becomes part of the financial picture.
There is another concern for homeowners with an older, low-rate mortgage. A cash-out refinance could replace that low-rate mortgage with a higher rate applied to the entire remaining mortgage balance. A home equity loan or HELOC may leave the first mortgage in place, but it still adds a claim against the home.
Use home equity only after carefully considering job stability, emergency savings, housing costs, and the possibility of selling or refinancing later.
Nonprofit credit counseling or a debt management plan
A nonprofit credit counseling agency may help you build a budget, negotiate lower rates with participating creditors, and make one monthly payment through a debt management plan.
A debt management plan is different from taking out a new loan. It may require closing or restricting card accounts, and it does not reduce the principal automatically. It can be useful when your credit is not strong enough for a favorable personal loan or balance transfer.
Start with Ask The Money Coach’s debt management resources and compare counseling organizations carefully. Avoid companies that demand large upfront fees, guarantee that they can erase debt, or tell you to stop paying creditors without explaining the consequences.
Debt Consolidation Versus Debt Settlement
Debt consolidation restructures debt. You generally still repay the full principal, plus interest and fees.
Debt settlement attempts to negotiate a payoff for less than the full amount owed. It may involve stopping payments while money accumulates for settlement offers. That can damage credit, trigger collection activity, and create legal or tax issues.
Settlement may be considered in severe financial hardship, but it is not the same as consolidation and should not be treated as a cheaper version of a personal loan.
If your payments are already unaffordable, consolidating may only delay the larger problem. Consider speaking with a reputable nonprofit counselor, reviewing your budget, and learning what protections or formal relief options may apply.
What This Means for You
Debt consolidation is a financial tool, not a financial recovery plan.
Use the consolidation ledger before you apply:
- List every card balance, APR, minimum payment, and due date.
- Calculate your weighted average APR.
- Obtain realistic offers and record the exact APR, fees, and term.
- Compare total interest, not just monthly payments.
- Decide how you will prevent new card debt.
- Keep the difference between your old and new payment directed toward principal or emergency savings.
- Recheck the plan after 30, 60, and 90 days.
For more background, see ATMC’s comparison of cards, personal loans, and HELOCs and our resource on high-interest credit card relief.
ATMC Money Coach Box
Consolidation is usually worth considering when it produces a meaningful net interest savings, preserves a manageable payoff period, and comes with a behavior plan. If the cards will be used again, pause before consolidating. A lower rate cannot compensate for a growing balance.
FAQ
Is debt consolidation a good idea?
It can be a good idea when the new APR is meaningfully lower, fees are limited, the term is reasonable, and you can stop adding new debt. It is not automatically beneficial simply because it creates one payment.
Does consolidating credit card debt hurt my credit score?
Applying for a loan or balance transfer card may create a hard inquiry and temporarily affect your score. Paying down card balances can reduce credit utilization, which may help over time. Closing accounts can also affect your utilization and the average age of your credit accounts, so consider the broader effect before closing cards.
What is the difference between debt consolidation and debt settlement?
Consolidation combines debts into a new payment structure, usually while you repay the full amount. Settlement involves negotiating to pay less than the full balance. Settlement can have more serious credit, collection, legal, and tax consequences.
Should I use a home equity loan to pay off credit cards?
Only after carefully weighing the risks. A home equity loan may offer a lower rate, but it converts unsecured credit card debt into debt secured by your home. A cash-out refinance can also replace a low-rate mortgage with a higher-rate mortgage on the full remaining balance.
What is a 0% balance transfer and is it worth it?
A 0% balance transfer moves debt to a credit card offering a promotional interest rate. It may be worthwhile if the transfer fee is reasonable and you can pay off the balance before the promotional period ends. Check the post-promotion APR and avoid adding new purchases you cannot repay.
Why do people end up with more debt after consolidating?
They often continue using the paid-off cards while making payments on the new loan. A financial emergency, spending shortfall, or overly optimistic budget can also cause balances to return. Consolidation lowers the cost of borrowing, but it does not correct a cash-flow deficit by itself.
AskTheMoneyCoach Staff is the collective byline for our editorial team. Founded by Lynnette Khalfani-Cox, The Money Coach®, and Earl Cox, AskTheMoneyCoach.com publishes practical, research-informed guidance on credit, debt, saving, consumer protection, and everyday money decisions. Our work follows the site’s editorial standards and helps readers understand their options and make informed choices.