Before I tell you how to teach your kids about money, let me tell you what you don’t need: a perfect financial life. You don’t need to have paid off every debt, maxed out a retirement account, or never once bounced a check.
Parents come to me all the time feeling like they have to get their own house in order before they’re qualified to teach their kids anything about money. That’s just not true, and honestly, waiting for that kind of perfection means most families never start at all.
This guide is meant to be practical, not aspirational. It’s a set of real, usable ways to bring money into everyday family life, without turning it into a lecture series or a source of guilt.
I’ve spent years helping people understand money, and one truth keeps showing up: shame makes learning harder.
lf you grew up in a home where nobody talked about money (or maybe everyone argued about finances), if you’re rebuilding after a setback, or if you just wish you’d started sooner, you’re not disqualified from teaching your kids well. You can begin right alongside them and learn together.
KNOWLEDGE SNAPSHOT
| Parents should teach kids financial literacy through regular, age-appropriate conversations and real decisions. Explain your choices, let your kids manage small amounts, connect money to their goals, and review mistakes calmly. Move from observation to guided practice to independence. |
Begin with values, not vocabulary
Money lessons are also life lessons. What does your family want money to support? Security, generosity, education, freedom, faith, travel, entrepreneurship, caring for others?
You don’t need a formal family mission statement. Try one sentence instead: “In our family, we plan before we spend, we help when we can, and we don’t pretend mistakes never happen.” Kids remember principles that get repeated.
Make money talk normal
If kids only hear about money during an argument, they might learn that the subject itself is dangerous. Let them hear calm explanations during ordinary decisions instead.
At the store: “We’re buying the store brand because the ingredients are similar and the price is lower.” Before an outing: “We have $60 for the afternoon. Let’s decide what matters most.” After a mistake: “I missed a renewal date. I corrected it and set a reminder.”
Share the lesson, not the adult panic. Kids shouldn’t feel responsible for household bills.
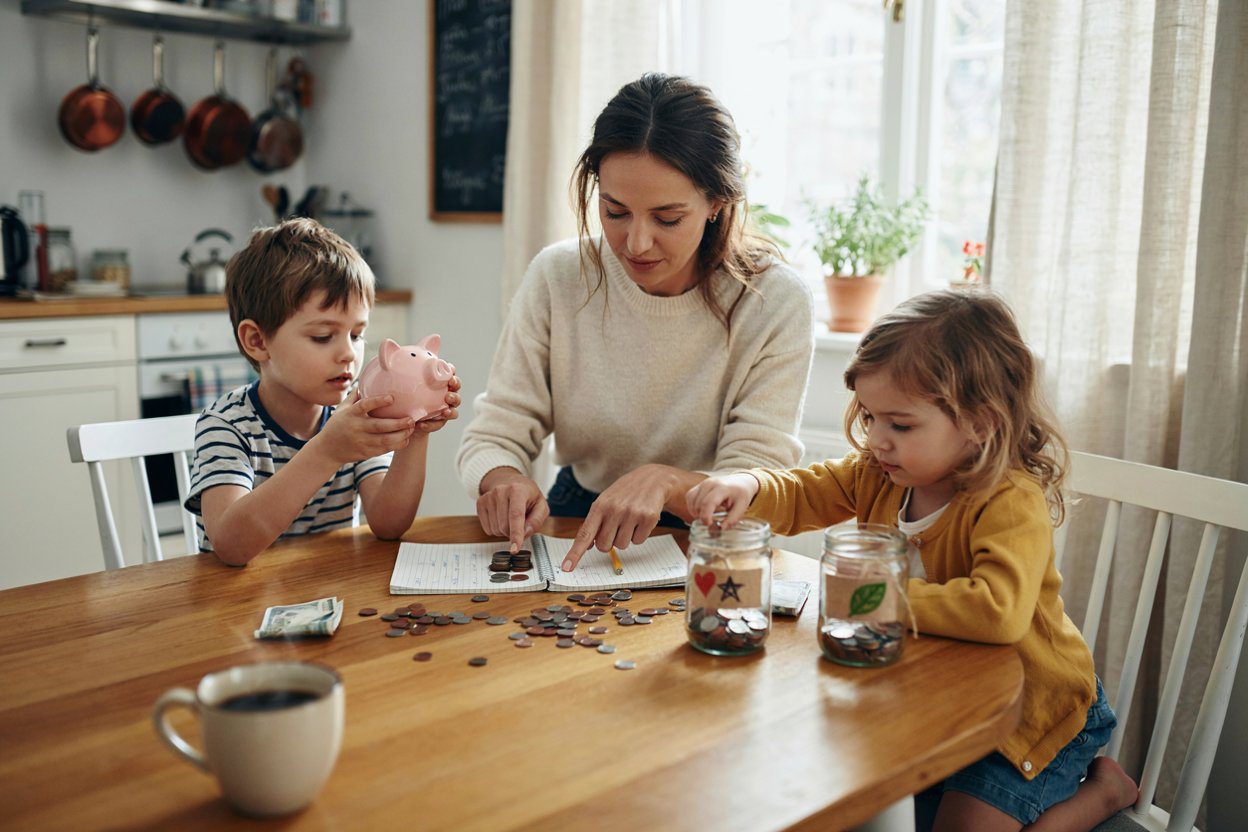
Give your child money to manage
Kids need a safe place to practice, and the amount can be small. Decide what the money is for, how often it arrives, and what boundaries apply.
For younger kids, use spend, save, and share categories. For preteens, add goals and simple budgets. For teens, add recurring expenses, digital payments, banking, and paychecks.
The hardest part for a lot of parents is allowing a non-dangerous mistake to actually happen. If your child spends all their money on Monday, don’t make them feel foolish. But don’t automatically refill the account on Tuesday, either. Empathy and accountability can live in the same house.
Teach earning without monetizing every responsibility
Kids benefit from contributing to family life simply because they belong to the family. They can also learn that extra effort, initiative, or creating value can produce income.
You might separate routine responsibilities from optional paid jobs. A child may be expected to keep their room reasonably clean, while washing the car or organizing a storage shelf is an additional paid task.
Older kids can explore work beyond the home: pet care, tutoring, lawn services, digital projects, or part-time employment. Help them think through expenses, time, safety, and a fair price.
Teach spending as a skill
“Don’t waste money” is too vague to actually help. Teach your kids to pause and ask: Do I want this, or do I want the feeling around it? What’s the total cost? What am I giving up if I buy it? Can I wait 24 hours? How will I know if it was worth it?
Our daughter Aziza gave us a real chance to practice this together when she asked for a pair of Uggs boots that cost close to $100. My husband Earl and I looked them up online and told her no, directly.
We explained she was still growing and probably wouldn’t get a full school year of wear out of them, so it just wasn’t the wisest use of that much money. She saved up her own money over time, and when she finally had enough to buy them herself, she decided to pass on the Uggs too. She ended up with a much cheaper pair of warm boots instead.
Sometimes the lesson isn’t getting what you originally wanted; it’s realizing on your own, with your own money on the line, that it wasn’t worth it after all.
For a teen, talk about advertising, influencers, buy now/pay later offers, and subscriptions. The goal isn’t suspicion of every purchase. It’s awareness.
Teach saving with named goals
Saving without a purpose can feel like deprivation. Let your kids choose at least one goal, and put a picture, an amount, and a target date somewhere they can see it.
Celebrate milestones without taking over. If your child changes the goal, talk about why. Revising a goal thoughtfully is very different from abandoning every plan at the first temptation.
Add credit, investing, and fraud prevention before adulthood
Teens should understand interest, APR, minimum payments, and credit reports before they ever borrow. They should know that investing involves risk, that diversification matters, and that online excitement is not the same thing as due diligence.
They also need a family safety rule: no legitimate institution will ever demand secrecy, gift cards, or immediate action under threat. If something feels wrong, pause and ask.
Match the lesson to your child’s age and wiring
The CFPB’s developmental framework recognizes that kids build financial capability over time. A 7-year-old might need concrete choices. A 12-year-old can practice habits and simple plans. A 17-year-old needs direct experience with real financial products and research.
Kids also differ in attention, anxiety, processing, and motivation. Use visuals, repetition, shorter sessions, or hands-on tasks when they help. Adapting the lesson isn’t lowering the standard; it’s opening the door wider.
Use tools thoughtfully
Life Hub is one of the most complete tools I’ve come across for this. It’s built for ages 6 to 18 and combines financial literacy with career readiness, entrepreneurship, and even AI literacy, all through Edu-Jobs that pay kids real cash weekly for the learning they complete.
It’s one of the few platforms treating financial education like it matters as much as any other subject a kid studies, by attaching real stakes and real rewards to it.
Families in Arizona, Arkansas, Indiana, Utah, New Hampshire, Louisiana, Wyoming, and Missouri can currently access it completely free through their state’s Education Savings Account program, with more states expected to join.
Electus, the company behind Life Hub, has also started offering a free live AI literacy course for teens ages 12 to 16, where kids learn how AI actually works, how to prompt it effectively, and how to use it safely and ethically, and they get paid for finishing it. That’s the kind of forward-looking, real-world preparation I want more platforms offering kids.
Whatever tool your family chooses, Life Hub, a youth bank account, jars, or a spreadsheet, stay in the loop yourself. Ask your child to teach one idea back to you. That simple reversal reveals real understanding and builds genuine confidence, in them and in you.
A 30-day family money plan
Week 1: Talk about one family money value, and let your child make one small spending decision.
Week 2: Set one savings goal and calculate a weekly target.
Week 3: Create one earning opportunity, or review a sample paycheck together.
Week 4: Review what worked, what felt hard, and what your child wants to practice next.
That’s enough. Consistency beats a perfect curriculum that never leaves the shelf.
FAQs: How to Teach Your Kids About Money
What age should financial education start?
Start with simple choices as soon as your child shows interest. Add complexity gradually rather than waiting for one big “money talk.”
Should children receive an allowance?
Allowance can provide good practice, but families differ on whether it’s automatic, tied to responsibilities, or split between basic and optional tasks. Clarity and consistency matter more than the exact system you choose.
What if parents disagree about money?
Talk through the rules privately first. Present a simple, shared approach to your child, and avoid asking them to take sides.
Sources
CFPB, Youth Financial Education

Lynnette Khalfani-Cox, The Money Coach, is a renowned financial expert, author, speaker, and media personality, empowering people to achieve financial success. Visit her personal website at https://lynnettekhalfanicox.com.